Authentication failures are fraud prevention failures
When authentication and fraud prevention operate in silos, account takeover attacks slip through. Here's what unified detection actually looks like.
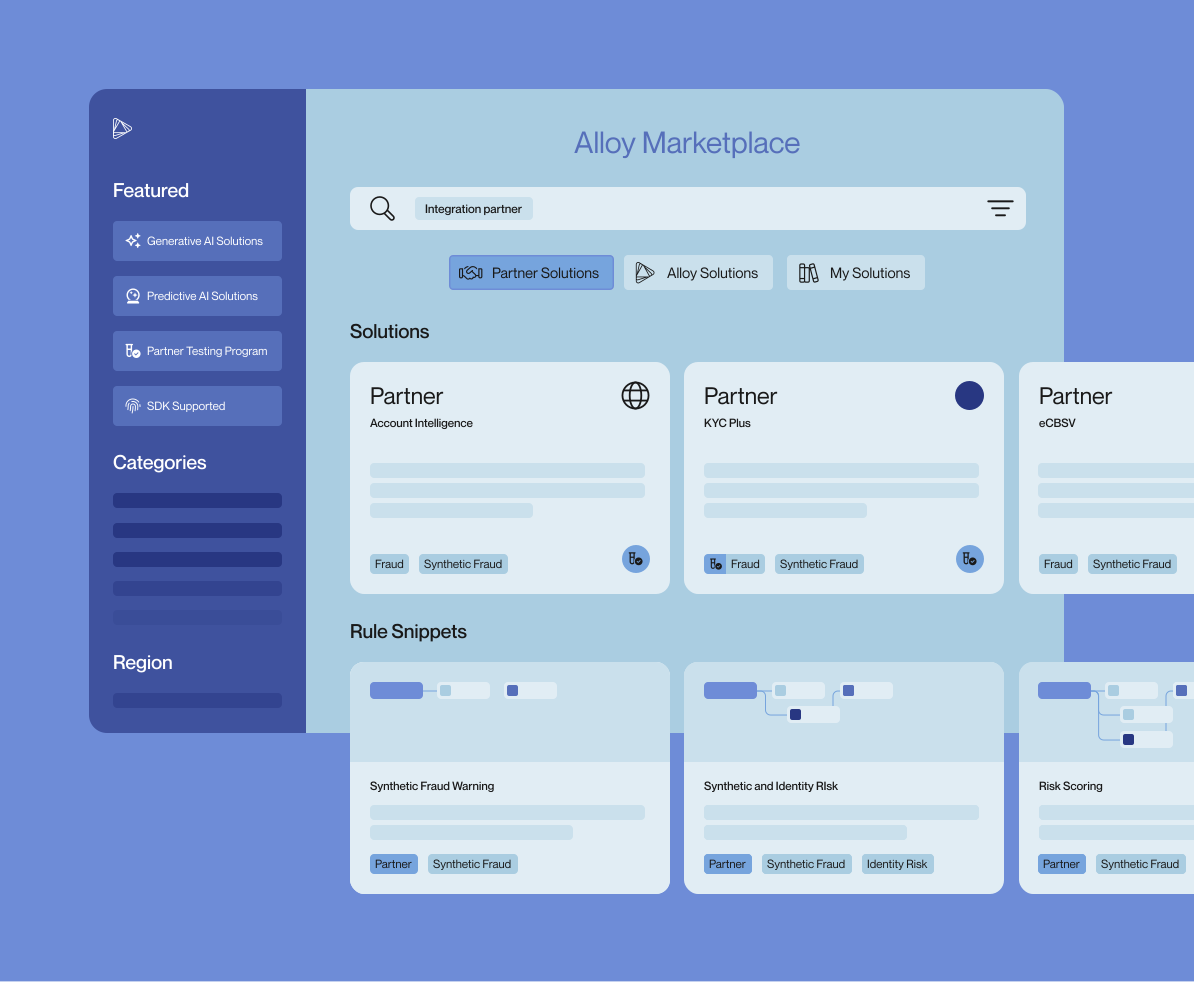
Alloy Marketplace unites 270+ partner solutions and a new library of pre-built decisioning logic in one dashboard. Discover, test, and deploy from one place.
Why spend time on tedious manual reviews when AI can do it for you? Learn how agentic AI for KYC and compliance is helping financial orgs optimize efficiency.
7th largest credit union in the U.S. drives growth by keeping members safe
Alloy’s real-time risk assessments helps IncredibleBank create a holistic risk profile for each applicant.
Alloy helps Earnest optimize customer onboarding and underwriting to boost conversion rates
Know Your Agent (KYA) is how financial institutions verify AI agents acting for customers. Learn the core controls and how it differs from KYC.
Learn how actionable AI empowers financial institutions and fintechs to move from detecting fraud to agile prevention.
Banks and fintechs run into challenges that cause customer friction when it comes to AML, KYB, and KYC regulations.
Risky Business: An Inside Look at How BECU Protects Its Members
Alloy President Laura Spiekerman took the stage at the Innovate Finance Global Summit to discuss how fintechs can protect their customers from emerging financial crime threats.
Alloy’s integration with BioCatch empowers financial institutions to provide secure and personalized account opening experiences
NEW YORK, May 13, 2025 -- BioCatch, which prevents financial crime by recognizing patterns in human behavior, today announced a new partnership with identity and fraud prevention platform provider Alloy. The deal fully integrates BioCatch’s end-to-end account opening (AO) solution into the Alloy platform, offering the more than 700 financial institutions and fintech companies that work with Alloy the opportunity to leverage BioCatch’s behavioral and device intelligence.“This is an exciting moment for us,” BioCatch Senior Director of Global Integration Jay Whoriskey said. “The integration of BioCatch’s behavior-based fraud-fighting tools into Alloy’s best-in-class orchestration platform has the potential to protect millions of consumers from account-opening fraud, while also offering a seamless digital experience.”Alloy’s platform seamlessly integrates more than 200 of the most innovative fraud-fighting and identity-verification tools on the market. With this new partnership,Alloy clients can easily add BioCatch’s account-opening protection to their fraud prevention toolset with no custom integration needed. BioCatch’s 2024 Digital Banking Fraud Trends in North America report documented a 59% decrease in AO fraud among the company’s American and Canadian customers, while 72% of the 600 fraud-management, anti-money laundering, and risk and compliance leaders surveyed for BioCatch’s 2024 AI, Fraud and Financial Crime Survey said their organization had encountered cases of synthetic identities when onboarding new clients.“In a world where AI has made financial fraud more scalable than ever, behavioral intelligence tools are essential for separating genuine customers from bad actors,” Alloy GM of Partner Solutions Brian Bender said. “Our integration with Biocatch will give Alloy’s clients another tool in their arsenal for fighting digital fraud in this challenging environment.” About BioCatch:BioCatch prevents financial crime by recognizing patterns in human behavior, continuously collecting more than 3,000 anonymized data points – keystroke and mouse activity, touch screen behavior, physical device attributes, and more – as people interact with their digital banking platforms. With these inputs, BioCatch's machine-learning models reveal patterns in user behavior and provide device intelligence that, together, distinguish the criminal from the legitimate. The company’s Client Innovation Board – an industry-led initiative in partnership with American Express, Barclays, Citi Ventures, HSBC, National Australia Bank, and others – collaborates to pioneer innovative ways of leveraging customer relationships for improved fraud detection. Today, more than 30 of the world's largest 100 banks and 267 total financial institutions deploy BioCatch solutions, analyzing 14.9 billion user sessions per month and protecting 511 million people around the world from fraud and financial crime.About Alloy:Alloy provides an identity and fraud prevention platform that enables global financial institutions and fintechs to manage identity risk so they can grow with confidence. Over 700 of the world’s largest financial institutions and fintechs turn to Alloy’s end-to-end platform to access actionable intelligence and the broadest network of data sources across the industry, as well as stay ahead of fraud, credit, and compliance risks. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world.
Discover how Alloy’s annual hackathon drives innovation, boosts productivity, and delivers real value to clients — with past projects like Alloy for Embedded Finance, a testing suite, and internal automation tools.
In this eBook, we explore how using multiple data source providers in your identity verification process can not only help you mitigate fraud risks, but also bring on more good customers.
How banks and fintechs can strike the right balance between a great customer experience and fraud risk prevention.
San Francisco, CA: Blend Labs Inc. (NYSE: BLND), a leading origination platform for digital banking solutions, announced today an expanded partnership with Alloy, a leading identity and fraud prevention platform provider.As part of the new agreement, Blend customers can now more seamlessly and cost-effectively access Alloy’s advanced identity and fraud prevention capabilities into their consumer banking solutions, ultimately building a safer and more trusted digital banking experience in order to grow their business.“Our partnership with Alloy helps us go beyond expectations, giving financial institutions the security and scalability they need to lend with confidence,” said Blend's co-founder and CEO, Nima Ghamsari. “With this expanded relationship, we’re making it even easier and more cost-effective for lenders to access top-tier risk and fraud prevention tools—seamlessly built into their workflows.”This latest evolution builds on a longstanding partnership between Blend and Alloy, which has been delivering integrated fraud prevention and compliance solutions across Blend’s deposit account and consumer lending products. Financial institutions using this joint solution are already seeing measurable impact, including Langley Federal Credit Union:"Earlier this year, Langley was hit with a fraud attack, but Alloy and Blend quickly caught it and stopped it,” said Cris Daly, Digital Product Manager at Langley Federal Credit Union. “Alloy detected nearly 700 fraudulent applications and automatically rejected them so that none of those fraudsters made it into our portfolio."Through identity orchestration, the partnership enables lenders to meet KYC (Know Your Customer) requirements and screen for fraud by leveraging a range of third-party data sources. Configurable workflows further enhance efficiency by intelligently sequencing these providers in a cost-effective and optimized manner, ensuring institutions can balance security, compliance, and operational ease.“Fraud prevention has become a critical need in the lending industry, as financial institutions seek smarter, more efficient ways to manage identity risk and grow their business,” said Keith Kettell, Chief Revenue Officer at Alloy. “By combining our expertise in fraud prevention with Blend’s industry-leading consumer banking platform, we’re equipping lenders with the tools they need to stay ahead of threats while also automating and simplifying their operations.”To learn more about Blend’s Consumer Banking solutions, visit blend.com/products/consumer-banking-suite.About BlendBlend Labs Inc., (NYSE: BLND) is a leading origination platform for digital banking solutions. Financial providers— from large banks, fintechs, and credit unions to community and independent mortgage banks—use Blend’s platform to transform banking experiences for their customers. Better banking starts on Blend. To learn more, visit blend.com.About AlloyAlloy provides an identity and fraud prevention platform that enables global financial institutions and fintechs to manage identity risk so they can grow with confidence. Over 600 of the world’s largest financial institutions and fintechs turn to Alloy’s end-to-end platform to access actionable intelligence and the broadest network of data sources across the industry, as well as stay ahead of fraud, credit, and compliance risks. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world. Learn more at alloy.com.
Chargeback fraud is on the rise, costing financial institutions and fintechs millions of dollars. Alloy's identity and fraud prevention platform can help.
An identity and fraud prevention platform is an end-to-end platform for managing fraud, credit, and compliance risk, providing the clearest picture of customers throughout the entire customer lifecycle.
Subscribe to our blog for the latest posts, resources, and events for all things banking and fintech.
NEW YORK, NY (March 24, 2025) -- IncredibleBank, a digital-focused community bank headquartered in Wausau, WI, has partnered with Alloy, a leading identity and fraud prevention platform provider, to provide faster service to improve its account opening process, helping the bank to accelerate growth and reduce manual reviews. "Before Alloy, our account opening platform leveraged a single data source and was completely manual," said Phil Suckow, VP of Innovation at IncredibleBank. "Our application volume varied month-to-month, from a few hundred to a few thousand applications, requiring significant back-end resources during spikes. Now, everything is instant."By leveraging Alloy, IncredibleBank significantly improved the bank's digital onboarding process and overall operational efficiency. Application review time was reduced by 88%, and manual reviews were reduced by 90%. IncredibleBank selected Alloy after evaluating several platforms, citing its robust automation capabilities, user-friendly interface, and proven success in mitigating fraud. Alloy's platform has enabled IncredibleBank to:Reduce new account approval times from 2-5 days to instant decisionsCreate holistic risk profiles for applicants by combining five different data sourcesReallocate a full-time employee from application reviews to sales-focused tasksIdentify and mitigate potentially fraudulent applications more effectively“The move to Alloy was strategic, improving our onboarding customer experience and driving business growth without added risk,” Phil Suckow, VP of Innovation at IncredibleBank added. “We needed a platform to automate KYC, KYB, and fraud at originations at an enterprise level. Alloy met those requirements and allowed us to leverage its platform across various business units.” "We are thrilled to partner with IncredibleBank to enhance their account opening process and drive their growth. Their mission is to grow their customers' entire financial relationship is one we wholeheartedly support and are proud to help the bank as they aim to provide an incredible customer experience," said Jamie Verdi, Head of Client Success at Alloy.To learn more about Alloy, visit http://alloy.com About AlloyAlloy provides an identity and fraud prevention platform that enables global financial institutions and fintechs to manage identity risk so they can grow with confidence. Over 600 of the world's largest financial institutions and fintechs turn to Alloy's end-to-end platform to access actionable intelligence and the broadest network of data sources across the industry, as well as stay ahead of fraud, credit, and compliance risks. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world.
London, 19 March 2025 -- More than two in three UK fintech companies (68%) are reporting higher fraud volumes compared with one year ago, according to new data published today by Alloy, a leading identity and fraud prevention platform provider to over 600 fintechs and financial institutions globally.79% of UK fintechs say they lost at least £500,000 to fraud in the 12 months to October 2024. Strikingly, two in five (38%) fintechs reported losses of between £1m and £5m in that time, and one in ten (9%) lost more than £5m. Alloy’s State of UK Fraud Report identifies three key factors impacting UK fintech’s response to rising fraud: Regulatory compliance weighs more heavily than the risk of financial or customer losses93% of fintech C-Suite leaders ranked regulatory penalties and reputational damage as the most concerning consequences of fraud - ahead of direct financial losses and the loss of clients (both 87%). In late 2024, the UK’s Payments Systems Regulator introduced mandatory reimbursement requirements for victims of APP scams, which require that the sending and receiving organisations each shoulder 50% of the reimbursement cost. As a result, 97% of UK fintechs agreed that it is critical for receiving payment service providers (PSPs) to have robust financial crime controls. Indeed, two-thirds (67%) of UK fintechs say the PSR’s rules are driving overall increased investment in fraud prevention.James Baston-Pitt, Alloy’s Head of Growth UK, EMEA and APAC, comments: “The UK is home to one of the most sophisticated anti-fraud regulatory regimes. However, domestic regulatory innovation can not solve the problem on its own. Fraud is a global, borderless issue. This creates challenges for all fintech companies - in particular, those that want to operate internationally or extend their services to non-UK customers. Fintech businesses are negotiating multiple regulatory regimes against a backdrop of AI-driven fraud that moves and adapts faster than regulations can keep up.”Crime rings are behind the majority of fraud eventsThree quarters (73%) of UK fintechs report that organised crime rings are responsible for the majority of the fraud events identified by their businesses. Less than a fifth (19%) attribute most fraud to customers acting knowingly (known as ‘first party fraud’) and just 8% believe customers who are coerced account for the most fraud cases. “Fraud is a numbers game, and AI is making that game faster, cheaper, and easier for crime rings,” adds Baston-Pitt. “But there are data signals that fintechs can track to distinguish the bad actors from genuine customers. The opportunity now lies in using AI and data-sharing to track certain behaviours, establish patterns created by criminal groups and use that knowledge to eliminate them.”Inadequate internal resources persist, but investment to prevent fraud is growingOf UK fintechs that say their organisations are not sufficiently equipped to respond to growing fraud threats, almost three in five (57%) identify insufficient people, tools and access to data as the top reasons for their unpreparedness. 43% say their current fraud prevention controls are insufficient. In the face of these deficits, 96% of UK fintechs report that they are investing in fraud prevention in 2025. There’s a consensus that these investments pay off: 92% of respondents agree that the amount of money their organisation saves thanks to fraud prevention outweighs its cost. Fintechs cite identity risk solutions as their top investment for reducing fraud rates. “Fintechs face a difficult challenge to equip themselves against an enemy that is continually shapeshifting,” concludes Baston-Pitt. “But it’s encouraging to see that the vast majority of firms look to fraud prevention investment as an outlay to support future growth.”The survey was comprised of responses from 118 decision-makers working in a director-level role or higher at fintech organisations in the UK. The report was conducted on behalf of Alloy by The Harris Poll, a global consulting and market research firm.About AlloyAlloy provides an identity and fraud prevention platform that enables global financial institutions and fintechs to manage identity risk so they can grow with confidence. Over 600 of the world’s largest financial institutions and fintechs turn to Alloy’s end-to-end platform to access actionable intelligence and the broadest network of data sources across the industry, as well as stay ahead of fraud, credit, and compliance risks. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world. https://www.alloy.com/uk
NEW YORK, March 10, 2025 -- Alloy, a leading identity and fraud prevention platform provider, today announced the launch of Fraud Attack Radar, a machine learning-powered solution that provides financial institutions (FIs) and fintechs with actionable intelligence on fraud threats targeting new account creation. The new solution helps organizations address rising fraud risks by alerting in real-time when a suspected fraud attack is happening, with actionable insights in the Alloy platform to contain, triage and investigate threats, giving FIs the ability to proactively fight fraud without impeding growth. According to Alloy’s 2025 State of Fraud report, 60% of FIs reported an increase in fraud events last year, and only 33% of FIs detected fraud events at onboarding, meaning organizations are leaning too heavily on transaction monitoring controls to catch fraud. With Fraud Attack Radar’s instant alerts, Alloy clients can move to a proactive approach to detection, enabling FIs to stop fraud before money has left their organization. Earlier detection at the point of account opening also enables organizations to save time and resources, minimizing the need for manual clerical work to rectify fraud-related issues.“Many financial institutions are already using AI to prevent fraud,” said Parilee Wang, Chief Product Officer at Alloy. “What sets Alloy apart is that we use AI not just to alert our clients to fraud attacks, but also to provide them with actionable guidance on how to respond. With the Alloy platform, a fraud attack very quickly goes from being a terrifying problem to a contained threat.”Fraud Attack Radar is a data model developed leveraging Alloy’s unique insights into both common and emerging fraud attack strategies targeting the financial services industry. The new solution helps predict the likelihood that a financial institution is undergoing a fraud attack - that is, a coordinated attack by bad actors to create fraudulent accounts using specific fraud attack patterns or strategies. When suspicious activity is detected, clients receive real-time alerts with digestible insights and can instantly deploy more conservative policies to stop the bleeding while keeping their funnel open for low-risk applicants, and reducing overhead for manual review teams. Alloy also streamlines clean-up efforts by providing details on the entities involved to enable further investigation and provides recommendations on how to reopen their funnels over time."Alloy's Fraud Attack Radar gives us the ability to tap into intelligence across Alloy’s broad network to help us identify fraud attack patterns,” said Jacob Salkovitz, VP, Consumer Product Team Leader at Cambridge Savings Bank. “Not only will these notifications allow us to take quick action to contain potential risk, they'll help us save time and resources in the long term so our teams can focus on having a unified and holistic view of identity within the Alloy platform, which will enable us to unlock a level of proactivity."Key benefits of the Fraud Attack Radar include:Actionable insights: whether it’s deploying ‘safe mode’ policies, conducting further due diligence on impacted applications or initiating an investigation, take immediate action within a single platform.Industry-wide onboarding intelligence: a model is only as good as the data you feed it. Alloy’s model is trained on high-velocity attack patterns seen across the financial services industry to improve model accuracy. Portfolio-level insights: Fraud Attack Radar is designed to work at a portfolio level, identifying trends across an entire population of applications. This gives organizations a holistic view of identity risk in addition to the individual/applicant view available within the Alloy platform. Seamless implementation: Existing Alloy clients simply need to opt into using Fraud Attack Radar to adopt it and begin seeing benefits. There are no complex configurations or additional setups needed. Fraud Attack Radar is the latest tool in Alloy’s suite of actionable AI capabilities. While other solutions typically only inform clients when suspicious activity is identified, all signals from Alloy’s models enable them to take immediate action, whether that is conducting an investigation or triggering a more conservative policy. Insights that are gathered throughout the customer journey will continually feed into Alloy’s machine learning models to compute the risk profile of clients – both at a portfolio level (Fraud Attack Radar) and also at an entity level (Entity Fraud Model) – so FIs and fintechs can always stay on top of their risk.Fraud Attack Radar is available immediately to all Alloy clients using the Alloy platform for account origination in the United States. For more information, visit www.alloy.com.About AlloyAlloy provides an identity and fraud prevention platform that enables global financial institutions and fintechs to manage identity risk so they can grow with confidence. Over 600 of the world’s largest financial institutions and fintechs turn to Alloy’s end-to-end platform to access actionable intelligence and the broadest network of data sources across the industry, as well as stay ahead of fraud, credit, and compliance risks. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world. Learn more at https://www.alloy.com/
London, United Kingdom, March 5, 2025 -- Flagstone, the UK’s largest savings platform*, has partnered with Alloy, a leading identity and fraud prevention platform provider, to deliver a seamless, automated onboarding experience for individual and business customers. The partnership allows Flagstone to approve new applications within seconds, without impinging on the highest standards of security and compliance, and integrate global data partners into a single dashboard.By leveraging Alloy, Flagstone’s enhanced KYC (Know Your Customer) controls ensure that every new client benefits from a streamlined and intuitive onboarding journey without compromising on rigorous verification processes.With £1.1 trillion lost to financial crime annually in the UK**, financial institutions must strike a delicate balance between security and speed. Traditional onboarding processes can be manual, slow and full of friction, discouraging customers from completing applications and leaving firms vulnerable to fraud. The situation is exacerbated by a surge in AI-driven impersonations, deep fakes and organised crime rings. Together these present greater challenges for companies whose duty it is to protect themselves and their customers from the risk of financial loss. Through its partnership with Alloy, Flagstone has automated its onboarding process, reducing friction, improving conversion and pleasing customers, all without compromising security. With Alloy, Flagstone has significantly upgraded from a legacy onboarding process that sometimes took several hours and required manual oversight. Now, Flagstone has vastly increased its average STP (straight through processing rates). As a result, the company can now offer savers access to the UK market’s widest choice of savings products faster than ever before.Francesco Fulcoli, Chief Compliance and Risk Officer at Flagstone, comments: “Alloy fully understands our ambition to take a data-led approach to analysing our users’ needs and translate that back into the sort of compliant and superior customer experience we want to provide. By digitising our AML/KYC processes with Alloy, we’ve sped up exponentially how quickly savers can begin to enjoy access to hundreds of savings accounts on a single platform. Speed with certainty delights customers, serves our bank partners well, and sets us up for continued market leadership for years to come. Alloy’s automated monitoring and decisioning tools ensure we can meet our regulatory obligations efficiently while offering our customers a fast and secure onboarding experience.”James Baston-Pitt, Alloy’s Head of Growth UK, EMEA and APAC, adds: “Businesses like Flagstone must maintain a constant balance between acting in the best possible interests of their stakeholders while also maintaining a brilliant customer experience. By partnering with Alloy, Flagstone is creating a secure and stable environment in which the business can swiftly verify customer identities without causing unnecessary friction or delays - something that is paramount to the successful operation of this fast-growing, in-demand business. We’re delighted to be the engine behind Flagstone’s latest innovation.”Founded in 2013, Flagstone has grown quickly in the last three years to become the UK’s largest savings platform as more savers than ever turn to cash as a way to maximise the interest earning potential on their money in a low-risk, high-return way. Today Flagstone handles around £16 billion in assets on behalf of its individual, business and charity customers. Flagstone customers generated cumulative returns of more than £500 million on their savings in 2024 through the platform. Flagstone is also the engine behind the savings proposition for over 1000 financial services providers with whom Flagstone has API integrations or partnerships.Founded in 2015, Alloy enables global fintech companies to balance risk with growth as they serve more customers around the world. Some of the world’s fastest-growing fintechs rely on Alloy’s identity and fraud prevention platform to test, launch, and scale new products while maintaining confidence in their customers and the trust of partner banks and regulators. From supporting single-use cases like customer onboarding to powering end-to-end identity risk management, Alloy’s configurable solutions for fraud and compliance risk, dedicated expert guidance, and extensive ecosystem of data partners enable fintechs to future-proof their growth.This announcement follows the recent news that Flagstone has recorded record growth, including a 46% increase in revenue to £55 million and a 49% rise in Assets under Administration (AuA) in the twelve months to 31 December 2024.* Based on number of banks on panel and savings accounts on platform** UK Finance Annual Fraud Report 2024About FlagstoneFlagstone is a fintech company located in London that’s recreating how people grow their money. Since 2015, Flagstone’s group assets under administration stand at around £16 billion and it has become the UK’s largest savings platform by the number of banks and savings accounts on its panel. Flagstone customers can gain access to over 220 savings accounts from 66 of the UK’s leading cash savings providers, from the largest incumbent banks to challengers. Flagstone’s total AUA is currently increasing by more than £1 billion per quarter as more customers look to maximise the interest earning potential while minimising risk. Originally created as a platform for individual savers to access and maintain multiple cash savings accounts in one single place, today Flagstone provides white-label and API-integrated capabilities for businesses to offer their own customers easy-to-use, adaptable and competitive savings options. Flagstone partners with many of the UK’s leading wealth management firms including St. James’s Place, and powers a range of savings products at financial services providers including Saga and Revolut.Flagstone Group Ltd is authorised by the Financial Conduct Authority (reference number 605504) under the Payment Service Regulations 2017 for the provision of payment services. www.flagstoneim.com About AlloyAlloy provides an identity and fraud prevention platform that enables global financial institutions and fintechs to manage identity risk so they can grow with confidence. Over 600 of the world’s largest financial institutions and fintechs turn to Alloy’s end-to-end platform to access actionable intelligence and the broadest network of data sources across the industry, as well as stay ahead of fraud, credit, and compliance risks. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world.https://www.alloy.com/uk
As fraud tactics become more sophisticated, staying ahead of emerging threats is critical for financial institutions and fintechs. That’s why we teamed up with American Banker for a webinar, Fraud in Focus: Predictions and Trends for 2025.
Industry experts Sara Seguin, Kristen O'Neill, and Mike Perkowski discuss the latest fraud landscape and strategies on preparing for the year ahead.
Learn which factors lead to bust-out fraud, and how to stop it. Protect your bank, fintech, or credit union from this sudden financial threat.
NEW YORK, February 25, 2025 -- Leveraging products from Amazon Web Services (AWS), Alloy’s identity and fraud prevention platform can now decision on more than eight billion financial events per month, an increase of more than 400%. Alloy, a fast-growing company that enables global financial institutions and fintechs to manage identity risk, has added nearly 200 new clients in the last year alone and was recently named to the Forbes Fintech 50 for the third consecutive year. The company has used AWS since its inception to ensure that it is able to scale its infrastructure alongside the growth of its business. “As Alloy and our clients grow, we need to be able to support an increased number of decisioning events,” said Charles Hearn, CTO and co-founder of Alloy. “At every stage of our growth, AWS has helped us to ensure we not only maintain the capacity for today, but also can easily scale for tomorrow.”To increase decisioning capabilities, Alloy leveraged Amazon Aurora Serverless, Amazon DynamoDB, and Amazon Simple Storage Service (Amazon S3) to support the creation of a data layer that can ingest 3,200 events per second per customer. As a result, Alloy can now compute approximately 1,200 real-time decisions per second, and onboard approximately 600 entities per second. To optimize database usage so that thousands of servers could be safely scaled during peak load, Alloy uses Amazon RDS Proxy, a fully managed, highly available database proxy that makes applications more scalable, more resilient to database failures, and more secure.“Over the course of this project, the Alloy team’s commitment to scaling alongside their clients was incredibly clear,” said Yan Leshinsky, vice president of Amazon Aurora at AWS. “We’re thrilled Alloy has chosen AWS to power their increased decisioning capabilities as they help more financial institutions all over the world build better and safer products.”Alloy’s current clients include some of the world’s largest financial institutions and fintechs, including Navy Federal Credit Union, Ally Bank and Carta. Alloy works with 25% of the top 50 banks in the U.S., including a top five bank, and six of the top 10 credit unions.About AlloyAlloy provides an identity and fraud prevention platform that enables global financial institutions and fintechs to manage identity risk so they can grow with confidence. Over 600 of the world’s largest financial institutions and fintechs turn to Alloy’s end-to-end platform to access actionable intelligence and the broadest network of data sources across the industry, as well as stay ahead of fraud, credit, and compliance risks. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world.
Alloy’s Principal Advisor of Fraud & Identity Risk, Sara Seguin, shares top takeaways from Alloy’s annual fraud report
JERSEY CITY, NJ, Feb 12, 2025 -- Data Zoo, a global leader in identity verification data, has announced a strategic partnership with Alloy, an identity and fraud prevention platform provider trusted by over 600 leading banks, credit unions and fintech companies, to provide enhanced global data for secure customer onboarding.The partnership integrates Data Zoo’s comprehensive global data assets into Alloy’s orchestration platform, enabling financial organizations to seamlessly incorporate both traditional and non-traditional data sources into their onboarding processes–whether for new or existing clients– while extending their international reach through a single API. The integration allows clients to leverage data as a primary or complementary method for identity verification, which is an effective tool to mitigate the impact of synthetic identity fraud and to reduce friction in the onboarding process. Alloy’s clients can now leverage Data Zoo’s solutions to onboard consumers across the world with a single API integration, reducing operational costs and accelerating time to market in new geographies. “Data Zoo’s mission is to empower businesses with critical access to identity data globally to boost financial inclusion and block out bad actors,” said Charlie Minutella, CEO of Data Zoo. “Partnering with Alloy allows us to bring our extensive global data into an established platform that is trusted by financial institutions and fintechs, helping them mitigate identity risks while expanding their customer base safely.”As financial institutions increasingly seek solutions to balance an effective global customer onboarding experience while maintaining compliance with Know Your Customer (KYC) and Anti-Money Laundering (AML) regulations, this partnership brings together the strengths of two industry leaders. Data Zoo’s vast global data coverage allows Alloy clients to access critical identity data from multiple markets, ensuring more accurate identity verification across borders. “Alloy's platform is designed to prevent fraud without hindering business growth,” said Keith Kettell, CRO at Alloy. “By integrating Data Zoo’s global data coverage, we are giving our clients the ability to confidently onboard more users in new geographies while staying compliant with regulatory standards.About Data ZooData Zoo provides identity verification data that enables financial institutions, payment platforms, and fintechs to confidently verify consumers and business identities in over 170 jurisdictions using a diverse set of authoritative data sources. Data Zoo’s direct access to international data sources and advanced data sequencing presents companies with a global, efficient, and secure alternative to KYC/KYB verification and compliance.Leading global financial institutions, payment providers, and fintechs trust Data Zoo to verify millions of customers while minimizing fraud and risk. Headquartered in New Jersey, Data Zoo has offices in Amsterdam, Australia, New Zealand, the Philippines, and Singapore. For more information, visit: www.datazoo.com.About AlloyAlloy provides an Identity and Fraud Prevention Platform that enables global financial institutions and fintechs to manage identity risk so they can grow with confidence. Over 600 of the world’s largest financial institutions and fintechs turn to Alloy’s end-to-end platform to access actionable intelligence and the broadest network of data sources across the industry, as well as stay ahead of fraud, credit, and compliance risks. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world.
For banks and fintechs, fraud prevention is more than a defensive benefit: It’s a growth and transformation driver.
Fraud trends and predictions, according to US decision-makers
NEW YORK, 28 January 2025 – Fraud professionals overwhelmingly agree (71%) that the majority of fraud attacks were committed by financial criminals and fraud rings in 2024, according to Alloy’s latest State of Fraud Report. The report tracks shifting trends in financial fraud, based on a survey of nearly 500 senior-level fraud decision-makers working at banks, credit unions, and fintechs in the U.S.Alloy’s study comes following new information revealing that losses resulting from fraudulent Paycheck Protection Program (PPP) loans and fraudulent unemployment claims totaled $255 billion, far higher than the U.S. federal government’s initial estimate of $100 billion, according to the December 2024 report from the U.S. House Select Subcommittee on the Coronavirus.This year’s data from Alloy indicates that financial institutions are better understanding how fraud is committed, as decision-makers at financial organizations ramp up efforts to detect and combat attacks. “In the last four years, we saw a massive uptick in organized financial crime, driven by PPP loan fraud that helped fund criminal organizations who then systematically targeted FIs and fintechs,” said Alloy Co-Founder and CEO Tommy Nicholas. “But it has taken these companies time to accurately understand who is responsible for these attacks, because, at first glance, it can look like a regular person woke up one day and decided to commit a crime (first party fraud). Understanding that most fraud is actually coming from organized crime rings has caused a big shift in how the financial services industry fights bad actors.”Fraud continued to rise across both consumer and business accounts in 2024, according to 60% of respondents in the report, with 31% of financial organizations incurring over $1 million in direct fraud losses.Unsurprisingly, 93% of financial organizations are planning to make ongoing investments in fraud prevention in 2025, with 64% planning to implement an identity risk solution. Although 93% of respondents believe that AI will be game-changing for detecting and preventing fraud, expectations for AI will be much more grounded in 2025 than the year prior, Nicholas predicted.“This year will see fewer overhyped promises about AI and more tangible applications of machine learning to address fraud in real-time,” Nicholas said. “Rather than relying on standalone AI tools, financial organizations will shift their focus to investing in platforms that centralize identity and fraud risk across their organizations.”Other key findings include:Fraud has grown the most among enterprise banks – banks with greater than $50B in assets – with nearly 70% reporting an increase in fraud events. 90% of respondents invest just as much time in preventing fraud in branches and other physical channels as they do in preventing fraud on digital channels.62% of respondents are increasing their investment in fraud prevention as a result of recent regulatory scrutiny. The survey was comprised of responses from 486 decision-makers working at a director-level role or higher in the financial services industry across the enterprise banking, mid-market banking, credit union, and fintech sectors. The report was conducted on behalf of Alloy by The Harris Poll, a global consulting and market research firm.About AlloyAlloy provides an Identity and Fraud Prevention Platform that enables global financial institutions and fintechs to manage identity risk so they can grow with confidence. Over 600 of the world’s largest financial institutions and fintechs turn to Alloy’s end-to-end platform to access actionable intelligence and the broadest network of data sources across the industry, as well as stay ahead of fraud, credit, and compliance risks. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world.