Authentication failures are fraud prevention failures
When authentication and fraud prevention operate in silos, account takeover attacks slip through. Here's what unified detection actually looks like.
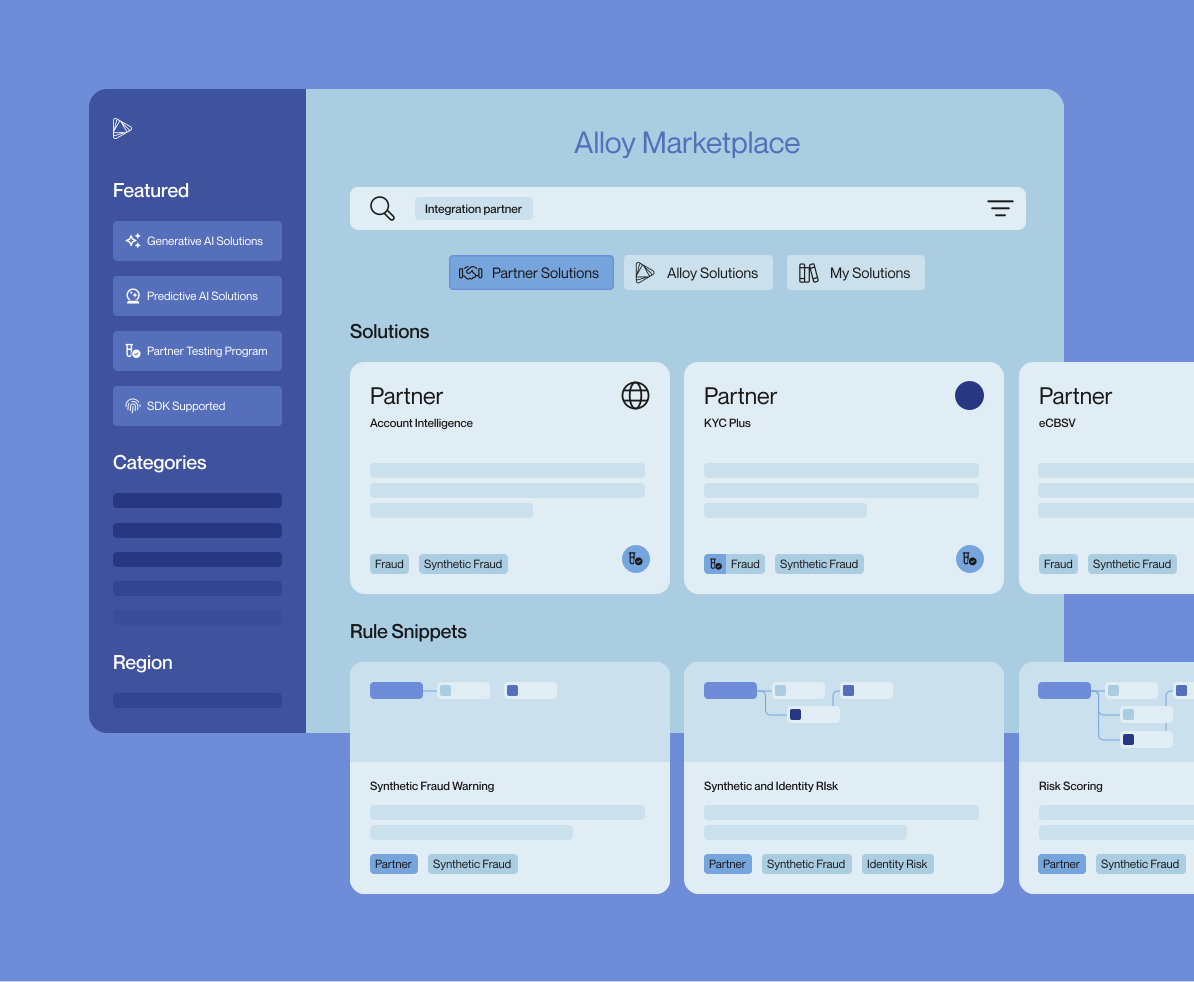
Alloy Marketplace unites 270+ partner solutions and a new library of pre-built decisioning logic in one dashboard. Discover, test, and deploy from one place.
Why spend time on tedious manual reviews when AI can do it for you? Learn how agentic AI for KYC and compliance is helping financial orgs optimize efficiency.
7th largest credit union in the U.S. drives growth by keeping members safe
Alloy’s real-time risk assessments helps IncredibleBank create a holistic risk profile for each applicant.
Alloy helps Earnest optimize customer onboarding and underwriting to boost conversion rates
Know Your Agent (KYA) is how financial institutions verify AI agents acting for customers. Learn the core controls and how it differs from KYC.
Learn how actionable AI empowers financial institutions and fintechs to move from detecting fraud to agile prevention.
Banks and fintechs run into challenges that cause customer friction when it comes to AML, KYB, and KYC regulations.
NEW YORK, February 25, 2025 -- Leveraging products from Amazon Web Services (AWS), Alloy’s identity and fraud prevention platform can now decision on more than eight billion financial events per month, an increase of more than 400%. Alloy, a fast-growing company that enables global financial institutions and fintechs to manage identity risk, has added nearly 200 new clients in the last year alone and was recently named to the Forbes Fintech 50 for the third consecutive year. The company has used AWS since its inception to ensure that it is able to scale its infrastructure alongside the growth of its business. “As Alloy and our clients grow, we need to be able to support an increased number of decisioning events,” said Charles Hearn, CTO and co-founder of Alloy. “At every stage of our growth, AWS has helped us to ensure we not only maintain the capacity for today, but also can easily scale for tomorrow.”To increase decisioning capabilities, Alloy leveraged Amazon Aurora Serverless, Amazon DynamoDB, and Amazon Simple Storage Service (Amazon S3) to support the creation of a data layer that can ingest 3,200 events per second per customer. As a result, Alloy can now compute approximately 1,200 real-time decisions per second, and onboard approximately 600 entities per second. To optimize database usage so that thousands of servers could be safely scaled during peak load, Alloy uses Amazon RDS Proxy, a fully managed, highly available database proxy that makes applications more scalable, more resilient to database failures, and more secure.“Over the course of this project, the Alloy team’s commitment to scaling alongside their clients was incredibly clear,” said Yan Leshinsky, vice president of Amazon Aurora at AWS. “We’re thrilled Alloy has chosen AWS to power their increased decisioning capabilities as they help more financial institutions all over the world build better and safer products.”Alloy’s current clients include some of the world’s largest financial institutions and fintechs, including Navy Federal Credit Union, Ally Bank and Carta. Alloy works with 25% of the top 50 banks in the U.S., including a top five bank, and six of the top 10 credit unions.About AlloyAlloy provides an identity and fraud prevention platform that enables global financial institutions and fintechs to manage identity risk so they can grow with confidence. Over 600 of the world’s largest financial institutions and fintechs turn to Alloy’s end-to-end platform to access actionable intelligence and the broadest network of data sources across the industry, as well as stay ahead of fraud, credit, and compliance risks. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world.
JERSEY CITY, NJ, Feb 12, 2025 -- Data Zoo, a global leader in identity verification data, has announced a strategic partnership with Alloy, an identity and fraud prevention platform provider trusted by over 600 leading banks, credit unions and fintech companies, to provide enhanced global data for secure customer onboarding.The partnership integrates Data Zoo’s comprehensive global data assets into Alloy’s orchestration platform, enabling financial organizations to seamlessly incorporate both traditional and non-traditional data sources into their onboarding processes–whether for new or existing clients– while extending their international reach through a single API. The integration allows clients to leverage data as a primary or complementary method for identity verification, which is an effective tool to mitigate the impact of synthetic identity fraud and to reduce friction in the onboarding process. Alloy’s clients can now leverage Data Zoo’s solutions to onboard consumers across the world with a single API integration, reducing operational costs and accelerating time to market in new geographies. “Data Zoo’s mission is to empower businesses with critical access to identity data globally to boost financial inclusion and block out bad actors,” said Charlie Minutella, CEO of Data Zoo. “Partnering with Alloy allows us to bring our extensive global data into an established platform that is trusted by financial institutions and fintechs, helping them mitigate identity risks while expanding their customer base safely.”As financial institutions increasingly seek solutions to balance an effective global customer onboarding experience while maintaining compliance with Know Your Customer (KYC) and Anti-Money Laundering (AML) regulations, this partnership brings together the strengths of two industry leaders. Data Zoo’s vast global data coverage allows Alloy clients to access critical identity data from multiple markets, ensuring more accurate identity verification across borders. “Alloy's platform is designed to prevent fraud without hindering business growth,” said Keith Kettell, CRO at Alloy. “By integrating Data Zoo’s global data coverage, we are giving our clients the ability to confidently onboard more users in new geographies while staying compliant with regulatory standards.About Data ZooData Zoo provides identity verification data that enables financial institutions, payment platforms, and fintechs to confidently verify consumers and business identities in over 170 jurisdictions using a diverse set of authoritative data sources. Data Zoo’s direct access to international data sources and advanced data sequencing presents companies with a global, efficient, and secure alternative to KYC/KYB verification and compliance.Leading global financial institutions, payment providers, and fintechs trust Data Zoo to verify millions of customers while minimizing fraud and risk. Headquartered in New Jersey, Data Zoo has offices in Amsterdam, Australia, New Zealand, the Philippines, and Singapore. For more information, visit: www.datazoo.com.About AlloyAlloy provides an Identity and Fraud Prevention Platform that enables global financial institutions and fintechs to manage identity risk so they can grow with confidence. Over 600 of the world’s largest financial institutions and fintechs turn to Alloy’s end-to-end platform to access actionable intelligence and the broadest network of data sources across the industry, as well as stay ahead of fraud, credit, and compliance risks. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world.
NEW YORK, 28 January 2025 – Fraud professionals overwhelmingly agree (71%) that the majority of fraud attacks were committed by financial criminals and fraud rings in 2024, according to Alloy’s latest State of Fraud Report. The report tracks shifting trends in financial fraud, based on a survey of nearly 500 senior-level fraud decision-makers working at banks, credit unions, and fintechs in the U.S.Alloy’s study comes following new information revealing that losses resulting from fraudulent Paycheck Protection Program (PPP) loans and fraudulent unemployment claims totaled $255 billion, far higher than the U.S. federal government’s initial estimate of $100 billion, according to the December 2024 report from the U.S. House Select Subcommittee on the Coronavirus.This year’s data from Alloy indicates that financial institutions are better understanding how fraud is committed, as decision-makers at financial organizations ramp up efforts to detect and combat attacks. “In the last four years, we saw a massive uptick in organized financial crime, driven by PPP loan fraud that helped fund criminal organizations who then systematically targeted FIs and fintechs,” said Alloy Co-Founder and CEO Tommy Nicholas. “But it has taken these companies time to accurately understand who is responsible for these attacks, because, at first glance, it can look like a regular person woke up one day and decided to commit a crime (first party fraud). Understanding that most fraud is actually coming from organized crime rings has caused a big shift in how the financial services industry fights bad actors.”Fraud continued to rise across both consumer and business accounts in 2024, according to 60% of respondents in the report, with 31% of financial organizations incurring over $1 million in direct fraud losses.Unsurprisingly, 93% of financial organizations are planning to make ongoing investments in fraud prevention in 2025, with 64% planning to implement an identity risk solution. Although 93% of respondents believe that AI will be game-changing for detecting and preventing fraud, expectations for AI will be much more grounded in 2025 than the year prior, Nicholas predicted.“This year will see fewer overhyped promises about AI and more tangible applications of machine learning to address fraud in real-time,” Nicholas said. “Rather than relying on standalone AI tools, financial organizations will shift their focus to investing in platforms that centralize identity and fraud risk across their organizations.”Other key findings include:Fraud has grown the most among enterprise banks – banks with greater than $50B in assets – with nearly 70% reporting an increase in fraud events. 90% of respondents invest just as much time in preventing fraud in branches and other physical channels as they do in preventing fraud on digital channels.62% of respondents are increasing their investment in fraud prevention as a result of recent regulatory scrutiny. The survey was comprised of responses from 486 decision-makers working at a director-level role or higher in the financial services industry across the enterprise banking, mid-market banking, credit union, and fintech sectors. The report was conducted on behalf of Alloy by The Harris Poll, a global consulting and market research firm.About AlloyAlloy provides an Identity and Fraud Prevention Platform that enables global financial institutions and fintechs to manage identity risk so they can grow with confidence. Over 600 of the world’s largest financial institutions and fintechs turn to Alloy’s end-to-end platform to access actionable intelligence and the broadest network of data sources across the industry, as well as stay ahead of fraud, credit, and compliance risks. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world.
AUSTIN, TX (JANUARY 22, 2025)— Q2 Holdings Inc. (NYSE: QTWO), a leading provider of digital transformation solutions for financial services, today announced a strategic partnership with Alloy, a leading identity and fraud prevention platform provider, to deliver a joint ongoing fraud monitoring solution for Q2 Digital Banking customers. Powered by Alloy’s centralized identity decision engine for fraud detection and prevention, this new solution addresses the growing need for financial institutions to take control of their fraud monitoring efforts while maintaining an engaging user experience and growing their business.Through this partnership, Q2 and Alloy will deliver a solution that addresses ongoing fraud risks, such as account takeover and peer-to-peer (P2P) payment fraud, that continuously threaten financial institutions. According to Alloy’s upcoming 2025 State of Fraud Benchmark Report one in three financial institutions lost over $1 million to fraud last year. Additionally, account takeover fraud was the most common fraud type by case volume identified by mid-market banks and credit unions in 2024. “The joint solution Q2 and Alloy are offering will go a long way towards enabling financial institutions to prevent fraud without hindering customer experiences, which is a very difficult thing to do,” said Matt Quale, President of Digital Banking at Forbright Bank. “I’m excited about this partnership’s ability to facilitate business growth and mitigate fraud losses for banks and credit unions.” Alloy will serve as the centralized identity decision engine, integrating Q2’s digital banking data, Q2 Innovation Studio, and Alloy’s robust data partner network to help financial institutions prevent more fraud. The ongoing fraud monitoring offering will be the first solution to actively ingest user activity signals coupled with fraud signals from multiple third-party data sources with the ability to interdict in real time on risky activities that may occur within the Q2 Digital Banking platform. “We believe that successful fraud prevention starts with a holistic approach to understanding identity,” said Parilee Wang, Chief Product Officer at Alloy. “That means not just tracking the suspicious movement of money, but also separating out the identities of fraudsters from those of genuine customers. Our joint solution with Q2 brings together the various data sources financial institutions need to more clearly understand their customer so they can better reduce criminal activity throughout the customer lifecycle.” By bringing together events in Q2 digital banking with industry-leading third-party data vendors in Alloy's identity-centric decisioning platform, the joint solution will provide real-time digital banking user action risk assessments and ongoing monitoring. The partnership will also help distinguish genuine customers from the risky ones ensuring that genuine customers benefit from a seamless digital banking experience while strategically introducing healthy friction for riskier customers.Additionally, it will improve operational efficiency via centralized decisioning and streamlined case management.“This strategic partnership between Q2 and Alloy represents an evolution in fraud prevention for financial institutions who leverage Q2’s digital banking platform," said Jim Mortensen, Strategic Advisor at Datos Insights. "By combining Q2's digital banking platform with Alloy's identity-centric fraud prevention and orchestration capabilities, Q2’s clients can leverage a more dynamic approach to fraud detection. What makes this partnership particularly compelling is the real-time risk assessment and interdiction capabilities coupled with the ability for client FIs to make timely modifications to their fraud detection processes rapidly. This approach should help Q2 clients strike that crucial balance between strong fraud prevention and maintaining the seamless digital experience consumers expect."“Banks and credit unions need scalable fraud solutions to combat growing fraud threats while maintaining an engaging customer experience,” said Jeff Scott, VP of fraudtech solutions at Q2. “Our partnership with Alloy will enhance existing native fraud monitoring capabilities within Q2 Digital Banking, providing a scalable, flexible, and identity-centric approach to fraud monitoring across digital channels. We are committed to continuously empowering our customers to help them fight against fraud and protect their account holders.”To learn more about Alloy and Q2’s new solution, please visit this link.About Q2 Holdings, Inc. Q2 is a leading provider of digital transformation solutions for financial services, serving banks, credit unions, alternative finance companies, and fintechs in the U.S. and internationally. Q2 enables its financial institution and fintech customers to provide comprehensive, data-driven digital engagement solutions for consumers, small businesses and corporate clients. Headquartered in Austin, Texas, Q2 has offices worldwide and is publicly traded on the NYSE under the stock symbol QTWO. To learn more, please visit Q2.com. Follow us on LinkedIn and X to stay up to date. About AlloyAlloy provides an Identity and Fraud Prevention Platform that enables global financial institutions and fintechs to manage identity risk so they can grow with confidence. Over 600 of the world’s largest financial institutions and fintechs turn to Alloy’s end-to-end platform to access actionable intelligence and the broadest network of data sources across the industry, as well as stay ahead of fraud, credit, and compliance risks. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world. Media Contact Maria Gari Q2 Holdings, Inc. [email protected] 315-657-0041 AlloyLarissa Padden202-841-4419 [email protected]
LONDON, 21 November, 2024 -- 10x Banking, the cloud-native core banking platform, has partnered with Alloy, a leading identity and fraud prevention platform, to deliver a next-generation customer onboarding, perpetual KYC and KYB monitoring, and credit decisioning platform for financial institutions globally.The partnership combines 10x’s pioneering meta core platform with Alloy’s leading solutions for managing identity risk throughout the customer lifecycle. 10x’s solution powers major financial institutions globally, including Chase UK and Westpac, and provides banks with the fastest, most cost-effective path to cloud-native transformation. Alloy’s platform is trusted by over 600 of the world's most prominent financial institutions and fintechs, including Sonovate, Liberis, Ent Credit Union, Shopify, and Clear Street. Alloy has pre-built integrations to one of the broadest networks of data products in the industry, with over 200 fraud, compliance, and identity data sources including Onfido, ComplyAdvantage, GBG and others covering 195 markets worldwide. On top of this, Alloy leverages its data orchestration capabilities to synthesise all of the data points and automate decision-making for clients, allowing clients to better solve for fraud, credit, and compliance risk, and grow with confidence. This partnership sees Alloy’s data network seamlessly integrated with 10x’s core banking platform, enabling financial institutions to make lending and account opening decisions with increased agility and precision from the core, delivering faster, better business decisions in a market that demands real-time capabilities. The modular decisioning solution allows financial institutions, for the first time, to originate, personalize, and manage loans directly within the 10x Banking platform.Keith Kettell, Chief Revenue Officer at Alloy said: “Our partnership with 10x Banking is a testament to our commitment to helping financial institutions in the UK and beyond fight fraud. Our partnership will provide financial institutions all over the world with flexible tools to efficiently manage identity risk, specifically aiding them in enhancing their account opening and in-life risk management processes.”Matt Mills, Chief Revenue Officer at 10x Banking, said, “Our collaboration with Alloy represents a significant step forward in the modernization of risk decisioning. Alloy’s cloud-native approach to identity risk management complements 10x Banking’s cloud-native core banking platform, creating a modern, versatile credit decisioning tool for banks and fintechs seeking to transform their loan origination processes. This partnership, with 10x’s unique meta core approach, enables us to continue our mission to revolutionize banking for the benefit of financial institutions, their customers, and society.”
RICHMOND, VA, November 13, 2024 -- CapTech Ventures, Inc. (CapTech), an award-winning technology consulting firm, announced today a strategic partnership with Alloy, the identity risk management platform behind over 600 of the world’s leading banks, credit unions, and fintechs. This collaboration leverages Alloy's scalable technology platform to enhance CapTech's offerings and delivery of innovative solutions in the financial services industry. "We are thrilled to embark on this partnership with Alloy," said CapTech CEO Andy Sofish. "Alloy’s expertise in identity risk management complements our commitment to providing secure and innovative solutions. This partnership allows us to enhance our offerings and help our clients improve their customer journeys."This partnership will give CapTech’s financial services clients access to Alloy’s comprehensive identity risk management solution alongside CapTech’s integration expertise, providing them with enhanced security, streamlined customer onboarding, and improved fraud prevention capabilities. Together, CapTech and Alloy aim to help banks, credit unions, and fintechs deliver a seamless and secure digital customer experience by ensuring that Alloy’s fraud and compliance solutions are properly integrated into financial institutions’ existing workflows, core systems, and customer management tools.“This partnership is an important tool for financial institutions looking for a seamless, innovative way to better prevent fraud,” said Keith Kettell, Chief Revenue Officer at Alloy. “CapTech’s deep understanding of technology and innovation, alongside Alloy’s extensive expertise in helping financial institutions manage their fraud, credit, and compliance risk, will allow more banks, credit unions, and fintechs to grow with confidence.” About CapTechCapTech is an award-winning consulting firm that empowers clients to achieve what’s possible through the power of technology. At CapTech, we’re passionate about the work we do and the results we achieve for our clients. From the outset, our founders shared a collective passion to create a consultancy centered on strong relationships that would stand the test of time. Today we work alongside clients that include Fortune 100 companies, mid-sized enterprises, and government agencies, a list that spans across the country. Learn more at captechconsulting.com.About AlloyAlloy helps solve the identity risk problem for companies that offer financial products. Over 600 banks, credit unions, and fintechs turn to Alloy’s end-to-end identity risk management platform to take control of fraud, credit, and compliance risks, and grow with confidence. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world. Learn more at alloy.com.
NEW YORK, October 3, 2024 -- Sonovate, the leading provider of embedded finance and payment solutions for the contingent workforce, today announced that it is implementing Alloy’s identity risk solution to better prevent fraud while also fueling growth.Alloy helps solve the identity risk problem for companies that offer financial products by enabling them to outpace fraud and confidently serve more people around the world. Over 600 banks and fintechs in the US, UK, and beyond turn to Alloy to grow with a clearer picture of their customers. Sonovate will use Alloy’s end-to-end identity risk management platform to stay ahead of rising fraud trends in the UK. A report from UK Finance found that £1.17 billion was lost to financial criminals in 2023. New technologies like generative AI have given bad actors more sophisticated tools to attack financial institutions. With Alloy, Sonovate is poised to stay ahead of this fraud risk while ensuring that genuine customers can efficiently access the company’s products and services.“With its network of data sources, Alloy gives us the power to protect our business and customers from financial crime and the flexibility to make adjustments as needed as our business scales,” said Tom Wilson, Global Head of Risk and Compliance at Sonovate. “We are excited for this next step in our global growth.”Since it was founded in 2014, Sonovate has funded nearly £6 billion ($8 billion) of invoices, supporting 3,300 businesses and 50,000 workers in 44 countries. In pursuit of the company’s global growth, Sonovate recently opened its first overseas office in Amsterdam and announced significant enhancements to its funding technology platform to better serve large, multinational recruitment businesses. Sonovate joins a growing list of UK-based banks and fintechs that use Alloy to solve for identity risk, including Liberis and Flagstone. “We’re excited to support Sonovate in their mission to empower recruitment and consultancy businesses with tailored financial solutions,” said James Baston-Pitt, Head of UK and EMEA at Alloy. “Risk management has always been a core part of Sonovate’s business, and with Alloy, the company will continue to evolve to address growing fraud threats.”About SonovateSonovate is the leading provider of embedded finance and payment solutions for the workforce. Its finance and technology services cater to recruitment businesses, consultancies, and labour marketplaces who place contractors and freelancers around the world. Sonovate’s platform and expert service deliver swift credit decisions, same-day funding, credit insurance and collection services as well as timesheet and workflow automation, empowering companies to concentrate on expanding their business, confident that processes and funds are in place to help meet payment deadlines. Since it was founded in 2014, Sonovate has funded nearly £6 billion ($8 billion) of invoices, supporting 3,300 businesses and 50,000 workers in 44 countries.About AlloyAlloy helps solve the identity risk problem for companies that offer financial products. Over 600 banks, credit unions, and fintechs turn to Alloy’s end-to-end identity risk management platform to take control of fraud, credit, and compliance risks, and grow with confidence. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world. Learn more at alloy.com.
BOSTON, October 1, 2024 -- Numerated, the leading AI-driven commercial lending platform, today announced its partnership with Alloy, the identity risk management company trusted by over 600 leading banks, credit unions and fintech companies, to deliver best-in-class fraud checks within commercial lending. This strategic partnership will supercharge Numerated's lending automation capabilities by combining cutting-edge risk management with advanced automation, providing unparalleled security and efficiency to financial institutions.In today’s environment, where fraud is an ever-present threat, this partnership will enable Numerated’s clients to perform robust fraud checks seamlessly within their lending processes. According to Alloy’s State of Fraud Benchmark Report, 100% of fraud decision-makers at banks and fintechs reported experiencing fraud in the last twelve months. Additionally, 96% of these institutions suffered financial losses due to fraud, with 70% reporting losses exceeding $500k during that period. This underscores the critical need for advanced fraud prevention in the financial sector, a need that Alloy’s platform will directly address within Numerated’s commercial lending solutions."Fraud prevention and lending automation are crucial in today's financial landscape," said Dan O’Malley, CEO at Numerated. "By partnering with Alloy, we are ensuring that our platform not only meets but exceeds the expectations of financial institutions looking for secure, scalable lending solutions. This partnership allows us to deliver the best of both worlds—top-tier risk management combined with the efficiency and speed of automation."The partnership will enhance Numerated’s platform in three key ways:Streamlined Onboarding: Automatically prefill customer data to optimize the onboarding process.Strengthened Fraud Prevention: Implement advanced KYC/KYB and AML checks to reduce risk and improve lending performance.Unified Digital Experience: Provide a seamless platform for capturing deposits and offering competitive lending products for SMB and commercial borrowers.“Alloy is excited to partner with Numerated to bring our identity decisioning technology to the commercial lending space,” said Keith Kettell, Chief Revenue Officer at Alloy. “Combining our expertise in fraud prevention with Numerated’s industry-leading lending platform will provide financial institutions with a powerful tool to mitigate risk while automating their lending operations.”This partnership represents a significant step forward in Numerated's mission to modernize business banking. With Alloy's technology, Numerated will continue to lead the industry by offering financial institutions a comprehensive solution that enhances security without sacrificing speed or user experience.About NumeratedNumerated is an AI-driven platform that transforms how financial institutions lend to businesses. By leveraging advanced data and AI, Numerated automates every step of the business lending process, from application to closing, providing lenders with industry-leading efficiency gains. Numerated’s platform is trusted by over 500,000 businesses and 30,000 lenders, processing over $50 billion in loans. Learn more at https://www.numerated.com.About AlloyAlloy helps solve the identity risk problem for companies that offer financial products. Over 600 banks, credit unions, and fintechs turn to Alloy’s end-to-end identity risk management platform to take control of fraud, credit, and compliance risks, and grow with confidence. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world. Learn more at alloy.com.
NEW YORK, September 24, 2024 -- Meridian Credit Union (“Meridian”), Canada’s second largest credit union, today announced that it is partnering with leading identity risk management company Alloy to provide a better user experience for new and prospective members while also reducing fraud risk. The partnership supports Meridian’s rapid growth, building on its years of commitment to serving Canadians and its base of 380,000 members, by providing the credit union with a centralized platform to manage fraud, credit, and compliance risk. Meridian joins the over 600 leading banks, credit unions, and fintech companies around the globe that rely on Alloy to help solve identity risk."Our members are at the heart of everything we do, so when searching for an identity risk platform, finding the most frictionless option was crucial. Alloy's ability to connect to hundreds of data sources allows us to test and select the vendors that will help create the positive Member experience we strive to deliver while minimizing risk, making it an easy decision for us,” said Matthew Seagrim, Chief Digital and Marketing Officer at Meridian. Alloy’s end-to-end identity risk management platform allows Meridian to identify good customers at origination, while preventing bad actors from gaining access to the organization. Using Alloy’s 200+ data products covering 195 markets—including Canada—Meridian can easily test and make changes to their onboarding policies, optimizing them for growth. Alloy also gives Meridian the ability to perform step-up verification on risky applicants, keeping fraud rates low while cutting back on manual reviews. Alloy’s real-time decisioning capabilities allow Meridian to make faster, more informed decisions, augmenting the credit union’s ability to deliver a personalized, top-notch member experience.“Meridian is well known for providing a high-quality user experience to its members,” said Keith Kettell, Chief Revenue Officer at Alloy. “We’re excited to be a part of that experience by giving Meridian the tools to meet KYC and KYB requirements while also onboarding genuine individuals and businesses efficiently.”Meridian joins a growing number of credit unions that use Alloy to help solve for identity risk, including Navy Federal Credit Union, Suncoast Credit Union, and Mountain America Credit Union. About MeridianMeridian is Ontario’s largest credit union, and one of the largest in Canada. Guided by our purpose, “helping you achieve your best life,” Meridian delivers personal, and wealth financial business solutions to over 380,000 Members. Our bold Meridian for Good strategy is aimed at helping people get access to the money and advice they need; plan for a better future that is clean, resilient, and diverse; and be financially confident. Meridian has two operating subsidiaries: Meridian OneCap Credit Corp (“MOCC”) and motusbank. For more information, please visit: meridiancu.ca.We acknowledge the land on which we operate is the traditional territory of many nations including the Mississaugas of the Credit, the Anishinaabe, the Chippewa, the Haudenosaunee and the Wendat peoples and now home to many diverse First Nations, Inuit, and Métis. We also acknowledge that Toronto is covered by Treaty 13 with the Mississaugas of the Credit.About AlloyAlloy helps solve the identity risk problem for companies that offer financial products. Over 600 banks, credit unions, and fintechs turn to Alloy’s end-to-end identity risk management platform to take control of fraud, credit, and compliance risks, and grow with confidence. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world. Learn more at alloy.com.
NEW YORK, August 21, 2024 -- Alloy, the identity risk management company trusted by over 600 leading banks, credit unions and fintech companies, today released its 2024 State of Embedded Finance Report, a survey of over 50 decision-makers working at U.S.-based sponsor banks. The report found that while embedded finance programs drive significant revenue (over 50%) for sponsor banks, a majority (80%) of respondents reported that meeting embedded finance compliance requirements as a sponsor bank is challenging in the current environment. Alloy’s State of Embedded Finance Report comes at a time when sponsor banks in the U.S. face drastically increased regulatory scrutiny. According to data from Klaros Group, 25.6% of the FDIC’s formal enforcement actions have been directed at sponsor banks since the beginning of 2024. “Running a sponsor bank program is inherently complex because you have banks who are highly regulated working with companies that are often new, fast-growing, and creating entirely new ways for consumers to interact with money,” said Tommy Nicholas, CEO and co-founder of Alloy. “Despite the challenge, we’re already seeing sponsor banks respond to regulatory developments by investing in better controls, training, and adding to their compliance tech stack.”These recent compliance violations have resulted in financial consequences for sponsor banks: Alloy’s report found that 75% of sponsor banks have lost $100k or more due to compliance violations, with 39% reporting losses of $250K or more and 6% reporting losses of $1M or more. However, financial losses are far from the worst consequence of regulatory violations: decision-makers at sponsor banks rank reputational damage as the top consequence of mishandling fintech partners’ compliance. Alloy’s report found that sponsor banks’ top barriers to maintaining a compliant embedded finance program are 1) a lack of control over their fintech partners’ policy controls and 2) a lack of auditability of their fintech partners’ policy controls. Earlier this year, Alloy launched Alloy for Embedded Finance, a product that gives sponsor banks, electronic money institutions, and program managers in the U.S., U.K., and E.U. the ability to oversee the compliance policies of their fintech partners. Alloy for Embedded Finance directly addresses embedded finance providers’ need to have greater control and visibility into their fintech partners’ compliance programs. Today, Alloy also announced a new module within Alloy for Embedded Finance: Audit Access. Tools like Alloy for Embedded Finance are becoming more widely adopted by sponsor banks: Alloy’s report found that sponsor banks’ most likely course of action in response to regulatory scrutiny is investing in new compliance technology. “Using Alloy for Embedded Finance has been a game changer for our team,” said Teddy Gordon, Director of Data at Grasshopper Bank. “We can easily set KYC requirements for our fintech partners and then roll those policies out to our entire program all at once. We ensure we’re compliant across the board, and our fintech partners still get to manage their own risk tolerance.”Alloy’s State of Embedded Finance report was fielded from May 30th to June 5th, 2024 and includes respondents from sponsor banks in the U.S. with at least $2 billion assets under management (AUM). The report was conducted on behalf of Alloy by The Harris Poll, a global consulting and market research firm.For more insights, read the full report here. About AlloyAlloy solves the identity risk problem for companies that offer financial products. Over 600 banks, credit unions, and fintechs turn to Alloy’s end-to-end identity risk management platform to take control of fraud, credit, and compliance risks, and grow with confidence. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world. Learn more at alloy.com.
NEW YORK, July 2, 2024 -- Alloy, the identity risk management platform for companies that offer financial products, announced that Kathryn Cook has joined the company as its new Chief Marketing Officer (CMO) to support the company’s rapid, global growth. Cook joins the company following nine years at nCino (NASDAQ: NCNO), an Alloy partner and leader in cloud banking for the financial services industry. While at nCino, she helped lead the company’s global marketing and communications functions as it grew from an upstart to a leading provider of banking solutions and a publicly traded company. “Over the last few years, Alloy has grown in almost every way possible. We’ve expanded globally, added capabilities with new products, extended both our reach and the strength of our network through strategic partnerships, and seen significant client adoption across banking and fintech,” said Tommy Nicholas, Co-founder and CEO of Alloy. “But in my eyes, we are only just getting started. I couldn’t be more thrilled to welcome Kathryn to the Alloy team as our first CMO and partner with her as we enter our next phase of growth.”Founded in 2015, Alloy is trusted to solve the identity risk problem for over 600 of the world’s top financial services companies, including Stash, Live Oak Bank, Grasshopper Bank, Ally, M&T, Carta, Ramp, and Shopify.Alloy has grown extensively over the last year, adding new solutions, partners, and clients. Recent highlights include: Added over 200 new clients, including 12 of the top 50 U.S. banks; Expanded presence in the U.K. with new hires, clients, and triple-digit revenue growth since launching in the U.K. market in 2022;Saw strong double-digit growth bolstered by newly launched solutions including Ongoing Fraud Monitoring and Alloy for Embedded Finance;Deployed over 50 new data product integrations across more than 30 partners to help clients stay ahead of the pace of fraud, with access to an ecosystem of over 200 data integrations. New partners include Enigma, Quantifind, and TrueBiz; Continued to add new technology partners including Lumin Digital and Origence; Alloy is also integrated with nCino, Narmi, MANTL, Apiture, Prelim, Baker Hill, Blend, and Treasury Prime. “Over the last nine years, Alloy has established itself as a leader in identity risk and fraud prevention solutions for innovative fintechs and financial institutions through its best-in-class products, people, and partnerships,” said Cook. “The pace of fraud continues to increase, and I believe Alloy has a massive opportunity to help organizations of all sizes, worldwide, fight fraud, manage compliance risks, and grow with confidence. I am thrilled to be joining the company at this exciting point in its trajectory, and I look forward to helping further advance Alloy’s bold mission and accelerate its growth.” About AlloyAlloy solves the identity risk problem for companies that offer financial products. Today, over 600 banks and fintechs turn to Alloy’s end-to-end identity risk management platform to take control of fraud, credit, and compliance risk, and grow with confidence. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world. Learn more at alloy.com.
NEW YORK, February 29, 2024 -- Alloy, the identity risk management company behind nearly 600 leading banks and fintech companies, today announced Alloy for Embedded Finance, a new product custom-designed for sponsor banks, BaaS providers, and their fintech partners to collaboratively manage identity risk and stay ahead of regulatory requirements.Oftentimes, sponsor banks have not had sufficient oversight or control over whether their fintech partners have adhered to the banks’ government-mandated compliance requirements. Alternatively, in models where sponsor banks have taken on all compliance responsibilities, they have often forced their fintech partners into a one-size-fits-all approach to compliance that doesn’t suit fintechs’ evolving risk needs and often adds unnecessary friction to their user experiences.Alloy for Embedded Finance solves these challenges. The new product leverages the strength of Alloy’s existing platform while introducing a new parent/child account configuration. Sponsor banks (or ‘parent accounts’) have the ability to designate different levels of autonomy and guardrails for each of their fintech partners (or ‘child accounts’), depending on how mature the fintech is, how much of the process the fintech wishes to own, and the risk appetites of both parties. With this construct, sponsor banks can seamlessly build compliance policies, then issue and enforce them to each of their fintech partners all at once. More mature or 'autonomous' fintechs can customize their controls on top of these baseline policies, giving them the flexibility to tailor risk measures that don't add unnecessary friction for end users. Regardless of the autonomy level a fintech partner has, their sponsor bank retains total oversight of their policies to ensure they are fully compliant.“Sponsor banks can't operate without controlling the CIP/KYC and AML/BSA policies of the fintechs in their program—recent enforcement actions make this clear,” said Tommy Nicholas, CEO and Co-founder at Alloy. “At the same time, risk programs that are ‘one size fits all’ result in terrible user experiences for fintechs that pride themselves on providing a frictionless interface. Alloy for Embedded Finance solves both sides of this problem.”Alloy for Embedded Finance arrives during a period of massive potential for the embedded finance industry: Ernst & Young predicts that the global embedded finance market across the entire value chain will grow to $606B by 2025. However, the industry has been plagued by compliance challenges, with regulators increasing pressure on sponsor banks to ensure their third-party partners meet compliance requirements. According to data from advisory firm Klaros Group, sponsor banks drew one-third of all formal enforcement orders by federal banking agencies in the fourth quarter of 2023. With regulatory attention unlikely to slow down, it is more critical than ever for sponsor banks and their fintech partners to work collaboratively to meet compliance requirements so they can truly capture the full potential of the embedded finance market. Alloy already works with many of the leading sponsor banks, BaaS providers, and fintechs in this space, including Grasshopper, Liberis, Treasury Prime, and Marqeta.Learn more about Alloy for Embedded Finance here.About AlloyAlloy solves the identity risk problem for companies that offer financial products. Today, nearly 600 banks and fintechs turn to Alloy’s end-to-end identity risk management platform to take control of fraud, credit, and compliance risks, and grow with confidence. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world. Learn more at alloy.com.
London, UK, February 6, 2024 -- Liberis, the leading global embedded finance platform, today announced a partnership with Alloy, the identity risk management company behind over 500 of the world’s leading banks and fintechs. The partnership will enable Liberis to leverage Alloy’s platform to fast-track its global growth, and simplify the merchant experience by integrating automated compliance verifications into the funding application process. Additionally, it will facilitate the creation of custom, white-labelled onboarding experiences for partners. “We’re excited to partner with Alloy to help us achieve our global growth goals,” said Alexis Alexander, Chief Legal & Compliance Officer of Liberis. “Alloy’s platform will allow us to enter new markets quickly, optimise our merchants’ fully digitalised application for funding and scale to meet our partners’ demand, while also maintaining our high standards for compliance.” Alloy’s platform provides Liberis with access and integrations to a global network of over 190 data sources that help streamline KYC, KYB, and AML processes while also preventing financial crime. This will enable Liberis to onboard merchants in new markets quickly and efficiently. “We are thrilled to be partnering with Liberis to add them to our growing list of global clients,” said Tommy Nicholas, CEO at Alloy. “Alloy is designed to help businesses take control of fraud, credit, and compliance risk, while growing with the clearest picture of their customers. We’re confident that our partnership will help Liberis achieve its goals and provide its merchants with a seamless onboarding experience.” The collaboration between Liberis and Alloy will streamline the funding application process for merchants, minimising the paperwork involved. Most merchants will experience a smooth and seamless application process, with compliance verifications happening behind the scenes. In cases where further documentation is necessary, Liberis will offer a bespoke, white-label experience that aligns with the needs and standards of both merchants and their partners. “We hold ourselves to high standards on compliance, and we know it’s very important to our partners,” said Alexander. “But adding compliance checks can mean friction in the application journey. Using Alloy, we will be able to reduce this for most customers, whilst never compromising on a fully compliant process”. Liberis is committed to growing in a scalable way. By partnering with Alloy, Liberis can reduce the engineering resources required to support its international expansion and meet its compliance requirements. This allows Liberis to focus resources on its core mission of providing merchants with the funding they need to grow and thrive through their partners. About Liberis Liberis builds flexible embedded finance solutions that empower businesses and provide positive impact. Founded in 2007, Liberis is a leading global embedded finance platform with a mission to provide small businesses with accessible and responsible finance, based on the belief that funding should always be a positive force for small businesses. Liberis provides partners with the technology platform and financial solutions to offer hyper-personalised and accessible funding, empowering their small business customers to grow their revenues. With over 20 global strategic partners and direct reach to more than 1 million small businesses, Liberis has provided over $1bn of funding in over 60,000 transactions, enabling over 100,000 jobs to be created and saved. About Alloy Alloy solves the identity risk problem for companies that offer financial products. Over 500 banks and fintechs turn to Alloy’s end-to-end identity risk management platform to take control of fraud, credit, and compliance risks, and grow with confidence. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world. Learn more at alloy.com.
NEW YORK, January 25, 2024 -- Alloy, the identity risk management company behind over 500 leading banks and fintech companies, today released its 2024 State of Fraud Benchmark Report, finding that after years of steadily increasing fraud rates, the number of reported fraud attacks have begun to even out – and for some organizations, to decelerate. Despite that progress, fraud has still resulted in significant financial losses: 56% of respondents lost more than 500,000 (EUR/USD) to fraud in the last 12 months, and 25% lost over 1M (EUR/USD) in that time. Alloy’s State of Fraud Benchmark Report tracks shifting trends in financial fraud, based on a survey of over 450 fraud decision-makers working at banks, credit unions, and fintechs in the US and UK. The report offers an inside look at how companies prepare for, experience and respond to fraud, and how that fraud translates to direct financial losses. This year’s report revealed a drop in the number of companies that have experienced 1,000 or more fraud attempts over the past year: In 2023, 35% of companies experienced 1,000+ fraud attempts, down from 47% in 2022. But it’s not all good news: 61% of companies saw an increase in attempted fraud attacks committed through consumer accounts in the past year, and 54% saw an increase in attempted fraud attacks committed through business accounts. “It’s encouraging to see companies getting fraud volume under control using the wide array of identity data and technology available on the market,” said Tommy Nicholas, CEO and co-founder at Alloy. “But fraud remains a critical problem because bad actors are always finding new tools—such as generative AI—to steal increasingly large amounts of money.” On the bright side, business sectors investing in the implementation of new fraud tools were more likely to see decreased fraud attempts last year. 24% of enterprise fintechs and 43% of mid-market banks said fraud attacks by consumer and business accounts decreased at their organizations in 2023. At the same time, 37% of enterprise fintechs and 60% of mid-market banks said they were investing in the implementation of new fraud tools, suggesting that their use of outside technologies may be helping to diminish their fraud volumes. In 2024, more companies are poised to continue their investments in fraud prevention solutions: 75% of companies across all sectors said they plan to invest in an identity risk solution in the next year. Though identity solutions are helping companies make progress in the fight against fraud, certain types of financial crime continue to plague companies. Businesses across the US and the UK ranked authorized push-payment (APP) fraud as their top fraud driver last year by case volume and losses. Looking ahead, US/UK companies ranked AI-driven fraud (24%) as the type of fraud they are most concerned about in 2024. With both APP fraud and AI-driven fraud frequently resulting from scams targeted at individual consumers, many US/UK companies (53%) also plan to invest in anti-scam education tools over the next year. Alloy’s report was fielded in November 2023 and includes respondents from growth fintechs (1-100 employees), strategic fintechs (101-500 employees), mid-market fintechs (501-100 employees), enterprise fintechs (1000+ employees), regional banks (<$10M AUM), mid-market banks ($10B - $50B AUM), enterprise banks (>$50B AUM), credit unions/community banks, and online/pure play lending institutions. The report was conducted on behalf of Alloy by Qualtrics, a leading survey platform that powers more than one billion surveys every year. For more insights, read the full report here. About Alloy Alloy solves the identity risk problem for companies that offer financial products. Today, over 500 banks and fintechs turn to Alloy’s end-to-end identity risk management platform to take control of fraud, credit, and compliance risks, and grow with confidence. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world. Learn more at alloy.com.
NEW YORK, Nov. 30, 2023 — Narmi, a leading provider of digital banking solutions, today announced an integration with NeuroID, the leader in fraud detection through behavioral analytics. Facilitated by joint partner Alloy, the identity risk management company, the NeuroID solution marks a pivotal step in Narmi’s fight against fraud. The partnership will empower mutual clients leveraging the Alloy platform to use real-time behavioral insights that will revolutionize their approach to fraud prevention. NeuroID's technology tracks and analyzes an applicant's unique behavior during the account opening process, providing a valuable additional layer of data for fraud detection in Alloy and streamlining the user experience for legitimate customers. Jack Alton, CEO of NeuroID, said, “NeuroID is thrilled to integrate with Narmi via the Alloy platform. This partnership will give community and regional financial institutions access to an untapped suite of top-of-funnel digital insights that are critical to evolving fraud prevention efforts. Tracking digital behavior allows financial institutions to decipher between bad actors, bots, and fraud rings, and fast-track legitimate opportunities with precision and speed.” With almost five years of partnership, Narmi and Alloy continue to work to deliver impressive results for community and regional financial institutions. Financial institutions currently utilizing NeuroID via Alloy have seen reductions in fraudulent applications as high as 35%, showcasing the strength of the technology. The integration occurs seamlessly on the back end, demonstrating Narmi’s commitment to delivering an account opening experience that prevents fraud without sacrificing user experience. “Fraud is constantly evolving. As a custodian of Account Opening solutions to financial institutions, it's our responsibility to continue to advance our fraud and risk offerings so banks and credit unions can remain safe and protected,” said Edwin Akrong, VP of Product at Narmi. “Narmi is dedicated to ensuring that our customers always have the most effective fraud prevention tools.” Brian Bender, Vice President of Strategic Alliances at Alloy added, “Fraud is an increasingly growing and complex challenge so we are thrilled to bring NeuroID to Narmi’s current and future customers.” About Narmi New York City-based Narmi's digital platform empowers financial institutions to unlock the very latest capabilities in digital banking and account opening, enabling them to move faster, tap new growth opportunities, and achieve true digital transformation. The Narmi platform was built with the customer experience in mind, empowering financial institutions with an experience that is always effortless, current, and dependable. As a result, Narmi's customers are seeing as much as 3x account growth in less than 30 days and 4x deposit growth in as little as 90 days. Additionally, Narmi's financial institution clients are winning awards like Bankrate's 2020 Best Online Bank and Nerdwallet's Best Bank of 2021 for Online Experience. For more information, please visit www.narmi.com. About NeuroID NeuroID, the global leader in behavioral analytics, offers a friction-free, privacy-centered, and tailored solution to digital identity screening. After more than a decade of researching human-online interactions, our solutions provide a front line of defense by differentiating between genuine users and potential threats in real time. NeuroID solutions assess a user's intent—be it a genuine prospect, fraudster, or bot—by analyzing their interactions with a digital device. Our unique crowd-level insights, paired with expert guidance support modern risk management so global leaders can see fraud faster, reduce losses, and increase savings. Learn more at https://www.neuro-id.com/. About Alloy Alloy solves the identity risk problem for companies that offer financial products. Over 500 banks and fintechs turn to Alloy’s end-to-end identity risk management platform to take control of fraud, credit, and compliance risks, and grow with confidence. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world. Learn more at alloy.com.
NEW YORK, Oct. 18, 2023 -- Alloy, the identity risk management company, is expanding its credit underwriting capabilities to support banks, fintechs, and other builders of financial products in managing their holistic credit risk. In a challenging macro-environment, Alloy enables lenders to make smarter credit decisions, capture default risk, and increase revenue by identifying upsell and cross-sell opportunities. Alloy also automates credit line management and product remarketing, helping lenders maintain appropriate credit limits and proactively extend new product offers to customers. Lenders rely on Alloy’s established credit underwriting capabilities to offer credit products to more people with less risk. Alloy allows lenders to automate their credit decisions using identity data gathered during onboarding, credit bureau data, and alternative underwriting data. Lenders can make credit decisions using custom models, building anything from basic workflows to complex matrix models right within Alloy. Alloy’s updated credit offering builds upon these existing capabilities to offer a comprehensive and proactive approach to credit management beyond origination, enabling banks and fintechs to monitor for credit risk throughout the customer lifecycle. New features include: Automated, scheduled checks using the richest set of credit signals to monitor the ongoing financial health of borrowers: Lenders can incorporate fresh data pulls into their decisioning from a wide range of third party data sources: including credit bureau data, alternative underwriting data, and their own proprietary data. This comprehensive approach enables lenders to build a more complete picture of a borrower's creditworthiness and potential risks and carry out more data-driven decisions.Real-time alerts sent to lenders to notify them about changes in a borrower’s risk (e.g. if a borrower declares bankruptcy): Lenders can then take proactive measures to prevent the accumulation of high-risk loans.Automated line management: Lenders can maintain appropriate credit limits and terms through continuous monitoring to determine if customers qualify for a credit line change based on behavior and automatically conduct line adjustments.Automated credit remarketing process: Lenders can monitor positive customer behaviors like timely repayments and salary increases and can offer good customers new products, ultimately increasing their company revenue. “Historically, lenders have had to rely on point-in-time, siloed information about their borrowers,” said Parilee Wang, Chief Product Officer at Alloy. “With Alloy, lenders have a holistic solution for building a more complete picture of a borrower's ongoing creditworthiness and potential risks.” Alloy’s product investment in the credit space comes as U.S. consumer credit card debt has topped $1 trillion for the first time in history. As many borrowers face increased financial strain impacting their ability to repay debts, lenders may be forced to make difficult decisions about the creditworthiness of their applicants. At the same time, as revolving credit usage grows and consumers demand personalized, seamless experiences from their financial institutions, lenders are challenged with remaining top of wallet and staying ahead of competitors. “We were so excited to find a credit underwriting solution that lets us proactively manage our credit risk and allows us to rely on automated decisioning,” said Bobby Parker, Head of Credit at PEX Card. “The configurable platform allows us to be nimble, and we can make critical underwriting changes quickly with the appropriate controls in place. Furthermore, with the A/B test feature, and pre-built integrations with salient data providers, we can ensure our decisions are driven by data and information gain. Leaning on this solution will give us the ability to prudently grow our portfolio while driving strong risk adjusted returns.” Alloy offers the broadest coverage of third-party data in the industry with more than 190 data sources, including credit bureaus and alternative credit data providers. Some of Alloy’s partners in the credit space include: EquifaxExperianTransunionNova CreditFISZest AIPrism DataInscribeCodat About Alloy Alloy solves the identity risk problem for companies that offer financial products. Today, nearly 500 banks and fintechs turn to Alloy’s end-to-end identity risk management platform to take control of fraud, credit, and compliance risk, and grow with confidence. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world. Learn more at alloy.com.
NEW YORK, Aug. 15, 2023 -- Alloy, the identity risk management company, today released a report that found 60% of fintechs surveyed report paying at least $250,000 in compliance fines, with one-third paying over $500,000. The report also found larger fintechs were more likely to report higher compliance fines—37% of fintechs with 1,000+ employees reported paying over $500K in compliance fines last year. The State of Compliance Benchmark Report surveyed over 200 compliance decision-makers working at financial technology companies in the U.S. The survey ran from June 6-12, 2023, and included respondents from small (1-500 employees), medium (501-1000 employees) and large (1000+ employees) organizations. The report was conducted on behalf of Alloy by Qualtrics, a leading survey platform that powers +1B surveys every year. Nearly all fintechs (93%) reported that bank secrecy act (BSA) compliance requirements—including anti-money laundering (AML) and know your customer (KYC) requirements—were challenging to meet. Even so, most fintechs (80%) are doing more than the minimum amount of risk management required to meet these compliance requirements—suggesting a robust compliance program requires labor beyond even what is mandated by the U.S. government. "Because fintechs enable people to manage their money and make financial decisions, there's no wiggle room when it comes to compliance," said Gizelle Barany, General Counsel at Alloy. "In addition, the pace of bad actors is often faster than regulators are able to keep up with, so it's not surprising that many fintechs are doing more than the minimum to prevent financial crime." When it comes to the consequences of mismanaging compliance, while fintechs are concerned with fines, they are even more concerned about customer confidence in their ability to properly handle operations. According to 34% of fintechs, customer confidence had the greatest impact on their BSA compliance decisions, followed by reputational damage at 25%. Under the Bank Secrecy Act (BSA), financial institutions are required to assist U.S. government agencies in detecting and preventing money laundering, and report suspicious activity that might signal criminal activity (e.g., money laundering, tax evasion or human trafficking). Writing and filing suspicious activity reports (SARs), suspicious transaction reports (STRs), and currency transaction reports (CTRs) is a key part of compliance professionals' responsibilities, with 34% ranking it as the most time-consuming part of their work. More than one-third (36%) of fintechs filed anywhere from 5-10k SARs per year, with large organizations more likely to file 10-50k SARs. No matter an organization's size, SAR writing and filing is time-consuming: 25% of fintechs said that filing a SAR takes 1-2 weeks. For more insights, read the full report here. About Alloy Alloy solves the identity risk problem for companies that offer financial products. Today, nearly 500 banks and fintechs turn to Alloy's end-to-end identity risk management platform to take control of fraud, credit, and compliance risks, and grow with confidence. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world. Learn more at alloy.com.
SAN FRANCISCO, June 13, 2023 -- Astra, a leading provider of infrastructure for faster payments, today announced a partnership with Alloy, the identity risk management company, to streamline the onboarding process for existing Alloy customers to leverage Astra’s advanced transfer technology in their applications. “Astra and Alloy both aim to make the business of building fintech products and integrating faster, secure payments easier. By working together, we can improve the overall developer experience and help enterprises accelerate their time to market,” said Gil Akos, CEO and co-founder of Astra. “With Alloy’s identity risk solutions, businesses can confidently onboard verified customers. Paired with Astra’s best-in-class payment technology, more product owners and consumers can leverage accelerated settlement of funds.” Debit transfers are a convenient and secure way for businesses to send money to their customers. Yet, many organizations face overwhelming and unnecessary complexities in successfully facilitating them. With Astra’s platform, businesses can effortlessly create and send debit transfers to their customers’ bank accounts. Astra also offers a variety of features that make it simple for businesses to manage the lifecycle of payments, including a dashboard where they can track payment status and monitor transfer activity. “We’re thrilled to partner with Astra to help businesses offer faster payments,” said Brian Bender, VP of Strategic Alliances at Alloy. “Alloy’s identity risk management platform will help businesses quickly and safely onboard genuine customers and start offering debit transfers, without taking on additional risk.” As a result of this partnership, more businesses can now offer debit transfers and Visa Direct payments, improving customer experience and the growth of their business by freeing up critical developer time and resources. About Astra Astra offers advanced payment infrastructure, powering faster transfers for fintech products, financial institutions, and enterprises. Astra’s proprietary, vertically-integrated API enables developers to offer instant payments and accelerated bank transfers, with built-in optimizations to reduce risk. For more information, visit https://astrafi.com About Alloy Alloy solves the identity risk problem for companies that offer financial products. Today, nearly 500 banks and fintechs turn to Alloy’s end-to-end identity risk management platform to take control of fraud, credit, and compliance risk, and grow with confidence. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world. Learn more at alloy.com.
NEW YORK, March 21, 2023 -- Alloy, the leading Identity Decisioning Platform for banks and fintech companies, today announced its partnership with Kyckr, a corporate KYC company providing businesses with real-time data on prospective and existing customers and suppliers. The partnership gives Alloy’s 350+ clients — including Carta, Ramp, and Brex — a powerful tool in performing Know Your Business (KYB) for companies outside of the US. "With fraud higher than ever before, finding a speedy but safe way to onboard business customers remains a challenge for many financial institutions, particularly as they look to service clients in multiple global markets," said Edwina Johnson, Head of Global at Alloy. "Integrating Kyckr into Alloy’s platform will help our clients provide a seamless digital onboarding experience to customers without increasing the risk of fraud, no matter where in the world they are located." This partnership with Kyckr comes on the heels of Alloy’s UK launch in February, in which it strengthened its presence in EMEA with key senior hires and office space in London. Alloy first expanded to 40 new countries in 2022. Today, over 350 companies around the world use Alloy’s API-based platform to connect to more than 170 data sources, automate identity decisions during account origination, monitor them on an ongoing basis, and make credit underwriting decisions. Kyckr provides real-time access to aggregated corporate Know Your Customer (KYC) and Ultimate Beneficial Owner (UBO) data from over 300 company registries and primary regulated sources worldwide, helping organisations to avoid the significant regulatory and commercial costs associated with using poor-quality data. The partnership will strengthen Alloy’s ability to help financial institutions overcome the challenges of achieving seamless digital business onboarding on an international basis. “Tackling financial crime is the number one priority and it can only be achieved if companies can identify the criminals and meet the increasing scrutiny of regulators,” said Ian Henderson, CEO of Kyckr. “Our partnership with Alloy means its customers can automatically validate the status of companies at the respective corporate register in real-time, helping avoid the significant regulatory and commercial risks associated with using poor quality data.” To learn more about Alloy, visit https://www.alloy.com About Alloy Alloy helps over 350 banks and fintech companies make safe and seamless fraud, credit, and compliance decisions. Founded in 2015 and backed by leading investors from Lightspeed Venture Partners, Bessemer Venture Partners, and Canapi Ventures, Alloy’s platform connects companies to more than 170 data sources of KYC/KYB, AML, credit, and compliance data through a single API to help create a future without fraud. Learn more at https://www.alloy.com. About Kyckr Kyckr is a B2B information services company that aggregates, organises and structures the world’s primary source company data to help businesses reduce the risks associated with counterparty relationships. Unlike traditional data companies which source data from multiple, secondary sources, Kyckr provides accurate data with trusted, legally-authoritative provenance. This helps organisations to avoid the significant regulatory and commercial costs associated with using poor-quality data. Through the combination of accurate data with innovative technology, Kyckr’s solutions help businesses to succeed in the fight against fraud, money laundering and financial crime. Kyckr is wholly owned by serial entrepreneur and founder of WiseTech Richard White through his personal investment vehicle RealWise KYK AV Pty Ltd. Learn more at https://www.kyckr.com/.
CARMEL, Ind., Feb. 28, 2023 -- Baker Hill, a leading financial technology provider in delivering solutions for loan origination, risk management and analytics, has partnered with Alloy, an identity decisioning platform, to help financial institutions verify more prospective borrowers digitally and ensure compliance throughout the loan origination process. Through the partnership, financial institutions using Baker Hill NextGen® can now leverage Alloy Onboarding, which features a single-API identity decisioning platform, connecting multiple data sources into customized workflows during account origination. As a result, banks and credit unions can verify prospective borrowers quickly and accurately with fewer manual reviews and less fraud while complying with KYC and AML requirements. With integrations to more than 170 data sources, Alloy also gives Baker Hill's financial institution clients more flexibility to use the fraud prevention and identity solutions they prefer in their loan origination workflows. Additionally, Alloy makes it easy to incorporate new data sources or adjust workflows, eliminating the need for community financial institutions to rely on coding or costly programming to make changes. "There's been nearly a 7 percent increase in lending fraud among small and midsize businesses since 2020 and according to a 2021 report by Aite-Novarica Group, only 31 percent of lending institutions had negligible rates of fraud incidence," said Mike Horrocks, Vice President of Product Management at Baker Hill. "At the same time, many community banks and credit unions are focused on lending outside of their traditional markets to expand their reach, which can expose these institutions to added risk. By partnering with Alloy, Baker Hill helps minimize risk and time spent on manual reviews so financial institutions can generate loan growth with confidence, even in new markets." "For community financial institutions to remain competitive among borrowers, offering a seamless digital lending experience from day one is crucial," said Brian Bender, VP of Strategic Alliances at Alloy. "Together, Alloy and Baker Hill make it easier for banks and credit unions of all sizes to provide a world-class experience for borrowers while mitigating the risk of fraud and ensuring compliance. We are proud to work with an industry-leading fintech like Baker Hill and look forward to empowering their financial institution clients to accept more loan applicants without additional fraud risks." About AlloyAlloy helps over 360 banks and fintech companies make safe and seamless fraud, credit, and compliance decisions. Founded in 2015 and backed by leading investors from Lightspeed Venture Partners, Bessemer Venture Partners, and Canapi Ventures, Alloy's platform connects companies to more than 170 data sources of KYC/KYB, AML, credit, and compliance data through a single API to help create a future without fraud. Learn more at https://www.alloy.com. About Baker HillBaker Hill is in the business of evolving loan origination by combining expertise in technology with expertise in banking. Built on decades of walking alongside banks and credit unions as they provide vital resources to their communities, Baker Hill NextGen® is a configurable, single platform SaaS solution for commercial, small business, consumer loan origination, and risk management that grows along with you as your business needs change. Baker Hill is lending evolved. For more information, visit bakerhill.com.
LONDON, Feb. 9, 2023 -- US fintech Alloy has launched in the UK, strengthening its presence in EMEA with key senior hires and office space in London. Alloy's Identity Decisioning Platform helps banks and fintech companies to make smarter and faster decisions about the risk profile of each customer, and keep them safe from financial crime. The platform connects to more than 170 data sources, enabling financial institutions to automate customer approval and account opening, and monitor transactions in real time. Over 350 companies around the world trust Alloy to help them simplify processes and respond rapidly to new risks. Fraud is a more serious threat than ever before: 91% of financial institutions said that fraud has increased year-on-year, and 71% increased their spending on fraud prevention, according to recent Alloy data*. In the UK alone, bank fraud cost consumers almost £610M in the first half of 2022**. With Alloy, clients see an average 48% reduction in fraud. UK fintechs now have access to the company's full product range, enabling them to stay ahead of regulatory requirements and scale their operations with ease. Alloy's former COO Edwina Johnson has relocated to London to head up global expansion, while James Baston-Pitt, former Vice President at Onfido, will spearhead commercial initiatives as the EMEA Director of Growth. The UK team is currently hiring for roles across sales and partnerships, and will continue to build out its go-to-market and client services functions throughout the year. Since Alloy was founded in 2015, the firm has helped more than 350 of North America's most innovative banks and fintech startups prevent fraud and financial crime, including Carta, Ramp and Brex. Alloy has raised over $210M to date, reaching a $1.55BN valuation, and last year announced its expansion into 40 new countries. The company has doubled down on its commitment to EMEA by establishing a physical presence in London, its first local site outside the US. Edwina Johnson, Head of Global at Alloy said: "For financial institutions to remain competitive in today's market, cross-border functionality is no longer a major advantage - it's a must. Fintech startups are now building with a global mindset from day one, and looking for technology partners who can scale with them, adapting to their changing business needs, appetite for risk, and compliance requirements. "The UK is one of the world's most powerful fintech hubs, and we can't wait to help innovative local firms unlock their potential abroad. For too long, international expansion has involved trade-offs with risk management, but that doesn't have to be the case. Alloy provides dynamic support for companies operating across multiple regulatory environments, so they can focus on growing their business without worrying about the threat of fraud." To learn more, visit Alloy.com. *Source: Alloy's Annual State of Fraud Benchmark Report**Source: Reuters - Bank fraud falls from COVID high but threatens UK security About AlloyAlloy helps over 350 banks and fintech companies make safe and seamless fraud, credit, and compliance decisions. Founded in 2015 and backed by leading investors from Lightspeed Venture Partners, Bessemer Venture Partners, and Canapi Ventures, Alloy's platform connects companies to more than 170 data sources of KYC/KYB, AML, credit, and compliance data through a single API to help create a future without fraud. Learn more at https://www.alloy.com ContactLydia Woodward, consultant at LMW PR - [email protected] Sibilia at Alloy - [email protected]
NEW YORK, New York – February 7, 2023 Enigma, a data science company that provides comprehensive intelligence about the financial health and identity of every U.S. business, announced today they have partnered with identity decisioning platform Alloy, the leading onboarding and transaction monitoring solution for banks and fintech companies. Working together, Enigma and Alloy will provide financial institutions a rich, unified view of small and medium businesses, all within the Alloy platform. “Partnering with Alloy reflects our commitment to providing access to timely, accurate data about small and medium businesses,” said Charles Zhu, VP of Product at Enigma. “Alloy’s customers will now have access to monthly revenues and other financial health data to fuel credit decisions, right in the platform.” Enigma’s proprietary machine learning algorithms combine hundreds of public and private data sources to generate its data about the financial health of more than 30 million small and medium businesses. Now, Enigma’s data joins Alloy’s curated library of over 170 rich data sources, offered via Alloy’s API-based platform, empowering customers to automate identity decisions during account origination, monitor them on an ongoing basis and centralize credit decision workflows in one place. For financial institutions that leverage Alloy to grow and scale their operations, the partnership unlocks an all-in-one option for integrating Enigma’s small business intelligence for decision-making. Offering this new kind of data about small businesses, an underserved segment of the economy, delivers on Alloy’s mission of creating a more dynamic and accessible financial industry. “We’re creating a future where financial services are accessible for all, including the millions of small businesses that may fall outside the historic profile for what ‘creditworthy’ looks like,” said Brian Bender, VP of Strategic Alliances at Alloy. “Our partnership with Enigma gives financial institutions access to the timely data they need to say ‘yes’ to more small businesses.” About Enigma Enigma provides comprehensive intelligence about the identity and financial health of every small and medium business across the United States. By engineering better data from hundreds of public and third-party sources, Enigma provides a clear picture of a business and its operations, so that companies of every size can access the financial services they need to grow and thrive. Financial organizations from the world’s largest banks to tomorrow’s unicorns use Enigma's data to better serve their small business customers. To learn more visit https://enigma.com. About Alloy Alloy helps over 360 banks and fintech companies make safe and seamless fraud, credit, and compliance decisions. Founded in 2015 and backed by leading investors from Lightspeed Venture Partners, Bessemer Venture Partners, and Canapi Ventures, Alloy’s platform connects companies to more than 170 data sources of KYC/KYB, AML, credit, and compliance data through a single API to help create a future without fraud.
NEW YORK, Jan. 9, 2023 -- Leading Identity Decisioning Platform, Alloy, today released a report finding that 27% of respondents lost over $1M to fraud in the last 12 months. 70% of respondents reported losing over $500K to fraud, with fintech companies and regional banks being the most likely to report higher losses. 37% of fintech companies and 31% of regional banks estimated losing between $1-10M to fraud. The Annual State of Fraud Benchmark Report surveyed over 250 decision-makers working at financial institutions including community banks, fintech, crypto, national banks, regional banks, and online lending institutions). The survey ran from September 8-20, 2022, and respondents came from roles across fraud, compliance, risk technology procurement, digital banking strategy, and account opening. Fraud continues to plague financial institutions of all sizes and across all segments. One-third of respondents said they experienced between 1,000 and 10,000 fraud attacks in the last twelve months. 91% of respondents said fraud has increased year-over-year since 2021. "Fraud is the highest it's ever been," said Tommy Nicholas, CEO and co-founder of Alloy. "Rapid digitization and an influx of cash from pandemic relief scams have created the perfect conditions for fraudsters to thrive. Regardless of sector or size, financial institutions must do more to keep their customers' assets safe from fraud, but without compromising on the customer experience." The report also found that fraud prevention is a costly and time-consuming enterprise for financial institutions: two-thirds of respondents reported that over half of their workforce is working on fraud-related activities. 71% of respondents have increased their spending on fraud prevention YoY. Respondents were also concerned about additional 'hidden' costs of fraud such as legal repercussions, regulatory fines, reputational damage, and loss of clients. Respondents reported that the main barrier to defending against fraud is automation. 46% of respondents cited a greater need for automation as the most common barrier to being prepared to combat fraud, followed by an absence of dedicated teams for fraud (41%) and the inability to adapt to new threats (39%). For more insights, read the full report here. About Alloy Alloy helps over 360 banks and fintech companies make safe and seamless fraud, credit, and compliance decisions. Founded in 2015 and backed by leading investors from Lightspeed Venture Partners, Bessemer Venture Partners, and Canapi Ventures, Alloy's platform connects companies to more than 170 data sources of KYC/KYB, AML, credit, and compliance data through a single API to help create a future without fraud. Learn more at https://www.alloy.com
NEW YORK, December 1, 2022 -- Alloy, the leading Identity Decisioning Platform, will help crypto companies prevent fraud while also staying ahead of compliance requirements. New integrations will build on Alloy’s commitment to securing the next wave of crypto, working with leading customers in the space to power their onboarding solutions and transaction monitoring.Since 2015, Alloy has helped some of the most innovative banks and fastest growing fintech companies grow and scale operations, including Ally Bank, HMBradley, and Ramp. Alloy helps clients like these find more good customers and bring them into their products without increasing fraud risk. While traditional financial products have solved risk with friction, Alloy’s platform is designed for transparency and efficiency to safely onboard the next billion crypto users.“The time has come for crypto companies to take a future-forward approach to ensuring compliance is integrated into every step of their product lifecycle,” said Charley Ma, General Manager of Fintech at Alloy. “Alloy is ready to help our customers bridge this gap between regulation and implementation. With Alloy’s platform, crypto providers can safely assess any potential threats enabling faster transactions while mitigating regulatory drawbacks.”Alloy has formed new strategic partnerships with crypto-specific providers like Fiat Republic, Fortress, and Chainalysis. With the aid of these partnerships, customers can automate compliance measures, transaction monitoring, and identity decisioning for their end users, ultimately unlocking faster access to crypto platforms with reduced risk.“More regulation of the crypto industry in the US is imminent,” said Albert Forkner, CEO of Fortress Trust and former Banking Commissioner (WY). “In partnership with Alloy, our goal is to make it easier for Web3 companies to both become and remain compliant using purpose-built infrastructure.”“The vast majority of crypto transactions are legitimate, however, as global adoption of crypto grows, the number of illicit transactions is growing alongside it," said Jordan Bregman, Business Development Lead at Chainalysis. "Alloy’s data-driven identity decisioning insights coupled with Chainlaysis’ data and products can help stop criminals and help to prevent fraud and other illicit exposures, making cryptocurrency a safer and more accessible ecosystem for consumers around the globe.”To learn more about Alloy platform and capabilities to help crypto companies fight fraud, visit https://www.alloy.com.About AlloyAlloy helps over 300 banks and fintech companies make safe and seamless fraud, credit, and compliance decisions. Founded in 2015 and backed by leading investors from Lightspeed Venture Partners, Bessemer Venture Partners, and Canapi Ventures, Alloy’s platform connects companies to more than 160 data sources of KYC/KYB, AML, credit, and compliance data through a single API to help create a future without fraud. Learn more at https://www.alloy.com