Authentication failures are fraud prevention failures
When authentication and fraud prevention operate in silos, account takeover attacks slip through. Here's what unified detection actually looks like.
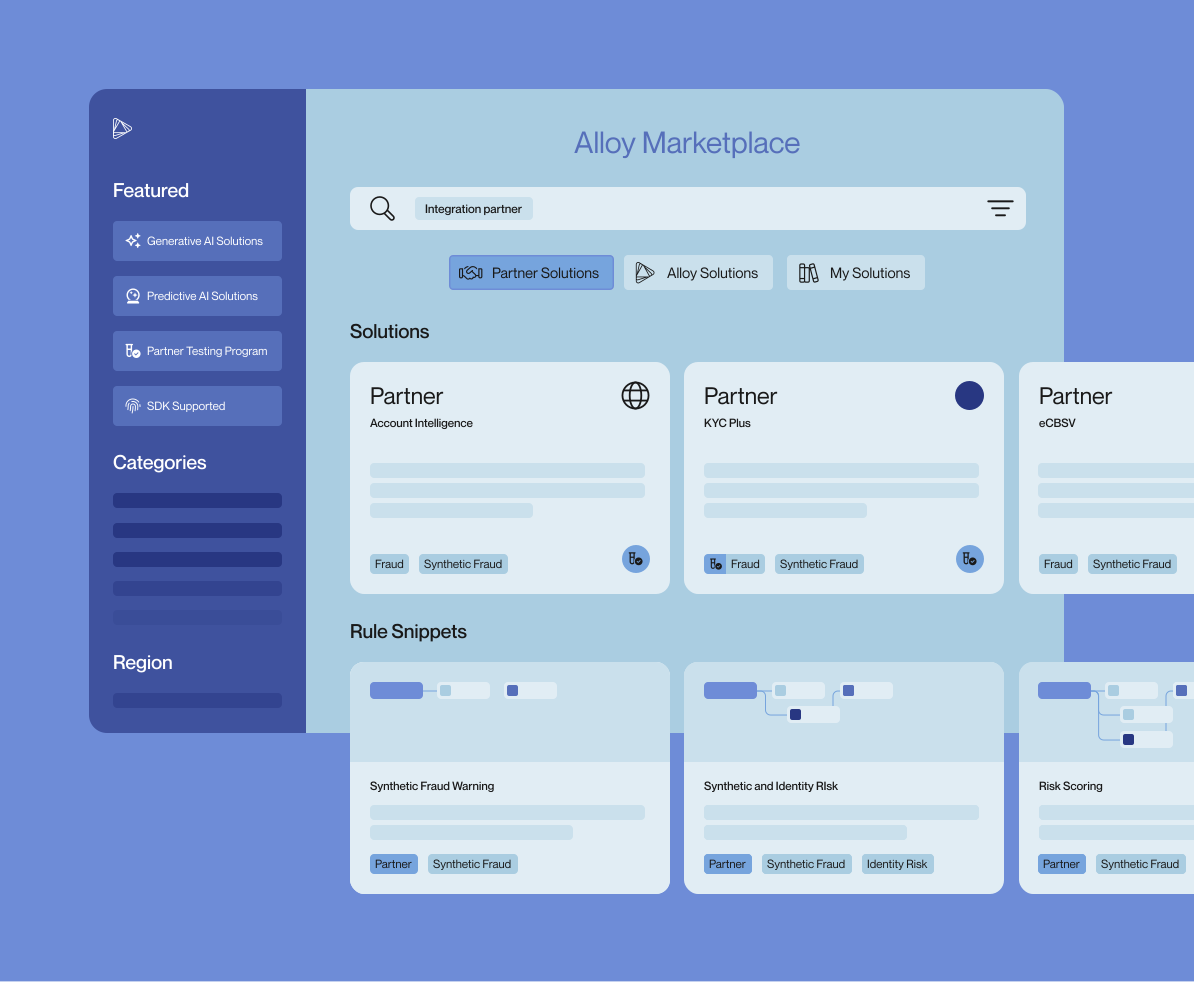
Alloy Marketplace unites 270+ partner solutions and a new library of pre-built decisioning logic in one dashboard. Discover, test, and deploy from one place.
Why spend time on tedious manual reviews when AI can do it for you? Learn how agentic AI for KYC and compliance is helping financial orgs optimize efficiency.
7th largest credit union in the U.S. drives growth by keeping members safe
Alloy’s real-time risk assessments helps IncredibleBank create a holistic risk profile for each applicant.
Alloy helps Earnest optimize customer onboarding and underwriting to boost conversion rates
Know Your Agent (KYA) is how financial institutions verify AI agents acting for customers. Learn the core controls and how it differs from KYC.
Learn how actionable AI empowers financial institutions and fintechs to move from detecting fraud to agile prevention.
Banks and fintechs run into challenges that cause customer friction when it comes to AML, KYB, and KYC regulations.
By rethinking customer onboarding with Clutch and Alloy, Launch Credit Union unlocked rapid growth and friction-right fraud protection
To support sustainable, scalable growth, Skyla implemented Clutch for digital account opening and Alloy for identity and fraud decisioning.
Catch a practical discussion between Alloy and Santander on how modernizing authentication can enable safe growth in a zero-trust world.
Join Alloy and Bank Director for an in-depth look at how institutions are confronting AI-enabled attacks and implications for the year ahead.
Tune in as Alloy and Ally Bank take an in-depth look at how the fraud landscape is shifting and implications for the year ahead.
In this eBook, we explore how using multiple data source providers in your identity verification process can not only help you mitigate fraud risks, but also bring on more good customers.
NEW YORK, December 9, 2025 – Alloy today announced the release of its annual State of Fraud Report, a detailed look at shifting trends in financial fraud, based on a survey of over 500 senior-level fraud decision-makers working at banks, credit unions, and fintechs in the U.S. This year, fraud professionals overwhelmingly agree (67%) that fraud events continue to rise, driven by bad actors’ use of new tools like generative AI to carry out their attacks on a greater scale.The impact of these fraud events also expanded in the last twelve months. Decision makers ranked losses due to goodwill credit to clients as the top reported consequence of fraud over the past year, and over one in five organizations (22%) reported losing over $5M in direct fraud losses. The true cost of fraud is likely even higher, as the majority (63%) of those surveyed reported that fraud losses are underreported. “One of the biggest changes to the fraud landscape has been the adoption of AI to combat fraud,” said Alloy Co-Founder and CEO Tommy Nicholas. “Bad actors are more sophisticated than ever, making the use of tools like AI table stakes in fraud prevention. In 2026, the distinction won’t be who uses AI; it will be how—specifically how to anticipate attacks and identify risk the moment it enters the system.”Other key findings include:AI is a driving factor in the rise of fraud: 91% of decision makers reported that more financial crimes are being committed with AI technology.In response, 82% of organizations stated they’ve increased their investment in AI-driven fraud prevention technologies.Synthetic identity fraud is the most common type of fraud by case volume:44% of respondents ranked synthetic identity fraud as the top fraud type tracked in their organization.89% also ranked synthetic identity creation as the most concerning fraud tactic when it comes to tactics that are evolving with AI.In addition to third-party fraud, first-party fraud and scams are rising threats for financial organizations:Fraud professionals attributed 36% of fraud events to organized fraud rings, 29% to customers intentionally stealing money from their financial institutions, and 29% to customers who were coerced or scammed.Online and mobile banking continue to be the most frequently targeted channels for fraud, although the frequency at which they are targeted shifted:Fraud in mobile banking rose by 7% year over year. Meanwhile, fraud in online banking saw a drop of 16%. Fraud prevention requires significant investment from financial institutions, but has a positive ROI:27% of organizations spend greater than 15% of their annual budget on fraud prevention; meanwhile,92% of decision makers report that their organization's fraud prevention efforts have helped them grow the business, and 84% reported that fraud prevention has resulted in higher rates of customer satisfaction.“This year’s report is a strong reminder that where there is money, there are bad actors looking for vulnerabilities to access it; and that those bad actors now have better tools than ever before,” Nicholas said. “But it also illustrates how far the industry has advanced when it comes to managing those risks. Most organizations are no longer looking at fraud as a threat, they are also considering how managing it can unlock their goals to provide a better experience, offer more products and increase customer loyalty.”The 2026 State of Fraud Report is based on responses from over 500 decision-makers working in a director-level role or higher in the financial services industry across the enterprise banking, regional and community banking, credit union, and fintech sectors. The survey was conducted on behalf of Alloy by The Harris Poll, a global consulting and market research firm.About AlloyAlloy provides an identity and fraud prevention platform that enables global financial institutions and fintechs to manage identity risk so they can grow with confidence. Over 700 of the world's largest financial institutions and fintechs turn to Alloy's end-to-end platform to access actionable intelligence and the broadest network of data sources across the industry, as well as stay ahead of fraud, credit, and compliance risks. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world. Learn more at alloy.com.
Get 2026 fraud trends and statistics for financial institutions and fintechs, and benchmark your fraud strategy to elevate your defenses.
Learn how financial institutions can predict and prevent seasonal fraud spikes. Explore tax season scams, holiday surges, and how actionable AI strengthens defenses.
Fintechs: What's the difference between KYC and KYB verification? How do KYC checks work? Alloy clarifies essential identity verification definitions.
Subscribe to our blog for the latest posts, resources, and events for all things banking and fintech.
Finding the right sponsor bank is key to fintech success. Learn what questions to ask around regulatory posture, compliance maturity, and scalability.
Discover how stablecoin regulation and global fintech adoption are reshaping payments. See how Alloy helps institutions and fintechs manage on-chain and off-chain risk.
How do you define “fraudster”? From ATO to wire fraud, Alloy’s ongoing list of financial fraud types and definitions keeps you in the know.
Credit underwriting is a tedious process. Amidst changing market demands and increasing customer expectations, Alloy helps you reimagine it.
Learn how financial institutions and fintechs can detect scams earlier, protect customers from losses, and strengthen their fraud prevention program.
Discover Alloy's Partner Center — a dynamic dashboard offering 250+ AI-powered data solutions to help financial institutions fight fraud and manage identity risk.
NEW YORK, October 21, 2025 – With criminals increasingly using AI to develop more convincing scams, consumers also expect their banks to use the most advanced AI tools to protect them from bad actors, according to the 2025 State of Scams Report from Alloy, a leading identity and fraud prevention platform provider. 85% of Americans worry that AI technology makes scams harder to detect; topping their concerns are AI-driven bank impersonations (28%), voice cloning phone calls (21%) and synthetic identity fraud (18%). While consumers report fears of AI being used against them, the majority also expect financial institutions to use AI to help fight fraud. Two-thirds (66%) of consumers say they are more likely to choose a financial institution that uses AI security measures to protect them. And 97% of customers indicated that fraud prevention and security measures are the most important factor when selecting a financial institution.The report, based on a Harris Poll survey of 2,000 American consumers, found that scams have become deeply personal:62% of respondents report they have been victims of a scam themselves or know someone who hasOver a quarter (28%) of respondents reported losing money as a result of a financial scam. Of those victims, 21% reported losing $5,000 or more.Consumers ranked emotional distress (29%) as the worst consequence of being scammed"The data confirms what we're seeing on the ground: AI hasn't made fraudsters more sophisticated, it's made them more efficient," said Sara Seguin, Alloy. "A single criminal can now launch thousands of personalized attacks in minutes. But here's what's fascinating: consumers get it. They're demanding banks use the same AI technologies to protect them." The report comes at a time when financial scams are pervasive. Another recent report from the Aspen Institute’s National Task Force on Fraud and Scam Prevention found that a majority of Americans say they get scam calls, emails, and texts at least weekly, and more than 50 million U.S. adults have lost money to an online scam or attack. Additional findings from the 2025 State of Scams Report include: Consumers hold banks responsible: Two-thirds (67%) of consumers said that financial institutions should reimburse lost money for scams even when the transaction was personally authorized. At 73%, Gen Z and Millennials were even more likely to expect reimbursement from their financial institution, compared to 62% of Gen X and Boomers. Privacy takes a backseat to protection: 69% of Americans are willing to trade some privacy for AI-powered scam protection Trust hangs in the balance: 87% would lose trust in their financial institution if it failed to notify them about attempted scams “As fraudsters’ use of AI tools accelerates, the scope and scale of authorized payment scams edge closer to a tipping point that threatens to upend the trust relationship across the whole financial system,” said Trace Fooshée, Strategic Advisor at Datos Insights. “As this stark reality settles in, financial institutions are racing to adjust their standards of care and investment priorities to amplify their use of AI tools and to reinvent a more deliberate and collaborative approach to managing and improving customer safety.”The full 2025 State of Scams Report is available here. About Alloy Alloy provides an identity and fraud prevention platform that enables global financial institutions and fintechs to manage identity risk so they can grow with confidence. Over 700 of the world's largest financial institutions and fintechs turn to Alloy's end-to-end platform to access actionable intelligence and the broadest network of data sources across the industry, as well as stay ahead of fraud, credit, and compliance risks. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world. Learn more at alloy.com.
Get insights on how scams are impacting consumers and reshaping trust in financial organizations.
Learn how NACHA’s 2026 ACH rule amendments strengthen fraud monitoring — and how Alloy helps financial institutions prepare and stay compliant.
Alloy shares proven fraud prevention best practices for credit unions, drawn from real-world successes.
Meet Hayman Chan, a Senior Solutions Architect at Alloy. Learn how he helps clients implement creative technical solutions, builds internal tools, and keeps things dynamic through collaboration and innovation.
Data orchestration platforms like Alloy deliver real-time, coordinated data access to support fraud prevention, compliance, and onboarding decisions.
Credit unions face rising fraud threats and limited resources. Learn how Alloy helps credit unions prevent losses, protect members, and scale fraud defenses.